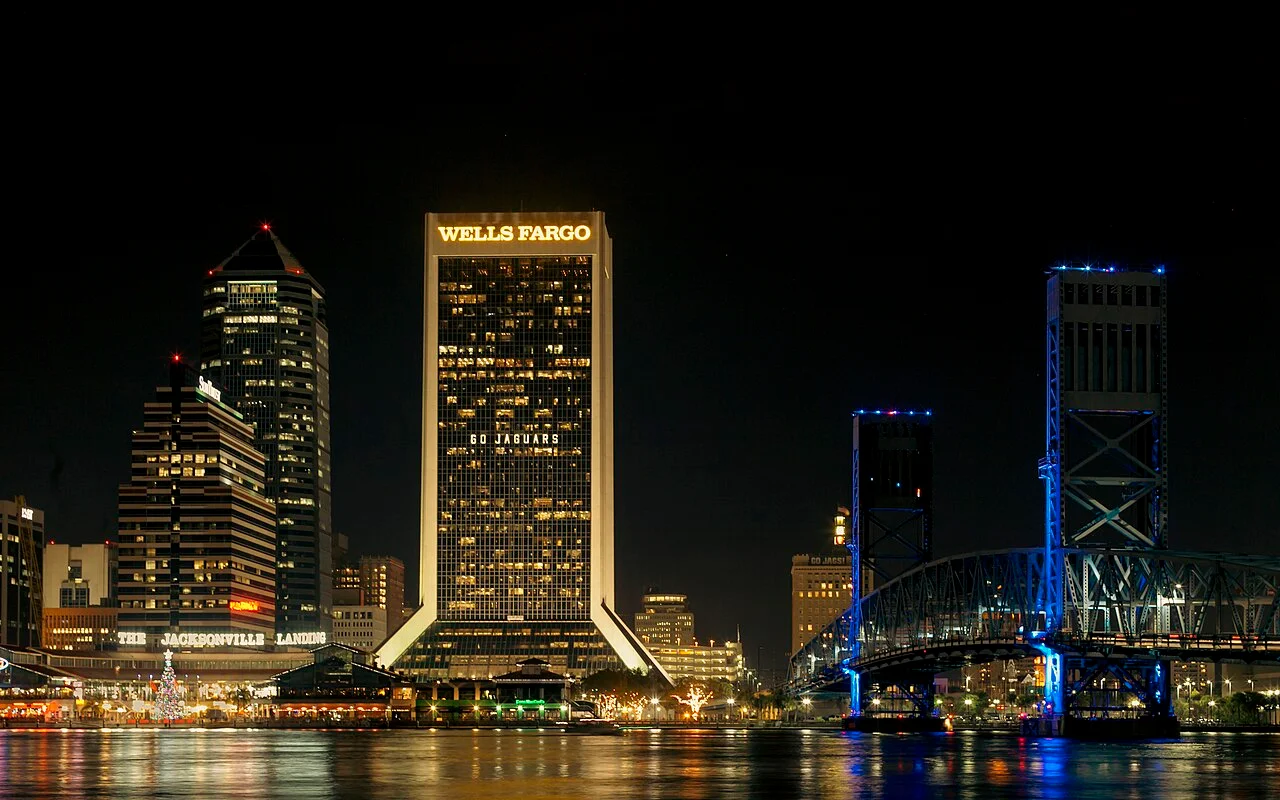
Quick answer: Jacksonville investment property in 2026 is Florida’s LTR cash-flow entry point, $200,000-$400,000 acquisitions, 6-8% gross long-term rental yield, and inland insurance that rarely destroys the pro forma the way coastal South Florida premiums do.
Jacksonville is the answer when an investor asks where Florida still pays rent on a spreadsheet without requiring a $500,000 down payment or a vacation-rental compliance department. While Miami absorbs international capital and Orlando owns the short-term rental yield conversation, the Jacksonville metropolitan area delivers something more utilitarian for portfolio builders: three-bedroom suburban homes that rent for $1,800-$2,400 per month on $240,000-$320,000 purchase prices, insurance bills that inland Tampa investors would recognise as normal, and landlord dynamics that do not depend on Mickey Mouse occupancy calendars.
Florida captured 21% of all US foreign buyer purchases in 2025 according to NAR, more than any other state for fifteen consecutive years. Latin American and European capital still concentrates in Miami-Dade, but domestic cash-flow buyers and first-time Florida landlords increasingly route through Jacksonville, where a $280,000 four-bedroom in Mandarin can produce gross long-term rental yields near 7% against carrying costs that leave net cash flow positive on conservative underwriting.
This guide is built for the jacksonville investment property buyer who prioritises LTR cash flow at entry-level capital: where to buy inside Duval County and adjacent St. Johns, how Jacksonville compares to Tampa Bay and Orlando on real numbers, which submarkets fit which budget, and how to model net yield before you wire earnest money. For the statewide framework, start with our Florida property investment guide. For gross-to-net math across all metros, see the Florida rental yield guide.
Disclaimer: Florida Estate provides independent research, not legal or tax advice. Yields cited are illustrative ranges drawn from 2025-2026 market data, not guarantees. Consult a Florida-licensed attorney, CPA, and broker before binding decisions.
Why Jacksonville Fits the LTR Cash-Flow Entry Thesis
Jacksonville’s investment case in 2026 is not built on pre-construction payment plans or nightly Airbnb arbitrage. It is built on affordability, military and logistics employment, port-driven trade, and rent growth that has tracked Sun Belt migration without the insurance shock that erases margin on coastal condos.
The metro’s demand drivers are practical rather than glamorous. Naval Air Station Jacksonville, Naval Station Mayport, and the surrounding defence contractor ecosystem create a rotating tenant base of military families on 24-36 month orders. The Port of Jacksonville, Florida’s largest container port by volume, anchors logistics, warehousing, and blue-collar employment corridors on the Westside and Northside. Healthcare systems including Mayo Clinic Florida, Baptist Health, and UF Health Jacksonville employ thousands of travelling nurses and permanent clinical staff who rent before buying locally.
For LTR investors, that tenant profile matters. You are leasing to households with stable W-2 income, military housing allowances, or healthcare contracts, not vacationers who cancel when airline prices spike. Twelve-month leases dominate; renewal rates run strong when properties are maintained and priced within 5% of market.
Gross long-term rental yields in Jacksonville typically run 6-8% on suburban single-family homes purchased at current market prices. Net yields land 4-6% after the standard Florida cost stack, roughly 1.5-2.5 percentage points below gross, tighter than many coastal markets but wider than Miami condo math where insurance and HOA fees alone can consume three yield points.
Florida Estate’s metro research consistently places Jacksonville in the cash-flow entry tier of the eight-market Florida map: the lowest purchase-price band among major metros, the highest gross LTR yields outside Orlando’s STR corridor, and the simplest regulatory environment for traditional landlords. Our best areas to invest in Florida 2026 guide ranks all eight clusters, Jacksonville sits in the LTR entry column alongside Tampa, below Orlando on STR gross yield but above every coastal luxury market on cash-on-cash return.
Jacksonville vs Tampa vs Orlando: Choosing Your Florida Strategy
Most buyers comparing Florida metros stop at headline yield. Professional underwriting compares entry price, net yield, tenant quality, appreciation tailwind, and operating friction together. Jacksonville, Tampa, and Orlando represent three distinct instruments on the same shelf.
Jacksonville is maximum cash flow at minimum capital. Entry from $200,000, gross LTR yields of 6-8%, inland insurance often under $3,000 per year, and straightforward landlord compliance. Appreciation is moderate, you are not buying the next Brickell skyline story.
Tampa Bay is balanced cash flow with stronger corporate relocation tailwinds. Entry from $250,000, gross LTR yields of 5-7%, slightly higher absolute rents, and a deeper professional-tenant pipeline from financial services and healthcare headquarters. See our Tampa Bay area guide for submarket detail.
Orlando/Osceola is gross yield maximisation through short-term rentals. Entry from $300,000 in overlay-eligible communities, gross STR yields of 6-10%, but mandatory overlay verification, DBPR licensing, combined STR taxes near 13%, and management fees of 20-25%. See our Orlando vacation rental investment guide and Florida STR regulations guide before assuming Orlando yield applies to every parcel.
| Dimension | Jacksonville | Tampa Bay | Orlando/Osceola STR |
|---|---|---|---|
| Primary investor thesis | LTR cash flow at entry capital | LTR cash flow + workforce growth | STR vacation rental yield |
| Entry price band | $200,000-$400,000 | $250,000-$500,000 | $300,000-$600,000 |
| Gross yield band | 6-8% LTR | 5-7% LTR | 6-10% STR gross |
| Typical net yield | 4-6% LTR | 3-5% LTR | 3-6% STR net |
| Insurance (inland SFH) | $1,500-$3,500/yr | $2,000-$4,500/yr | $1,500-$4,000/yr |
| Regulation intensity | Low, standard LTR | Low, standard LTR | Medium, overlay + DBPR |
| Appreciation tailwind | Moderate | Moderate-strong | Moderate |
| Best buyer profile | Portfolio builders, first Florida asset | Balanced cash flow + growth | Yield hunters accepting STR ops |
| Contrast luxury market | Miami appreciation play | Same | Same |
Reading the table: a buyer with $280,000 who wants the highest monthly net cash flow buys a Jacksonville suburban four-bedroom, not a Tampa Wesley Chapel townhome at $350,000 or an Orlando STR townhome requiring overlay proof. The same buyer who wants Florida exposure with maximum gross income and accepts nightly-rental operations buys in Osceola. None of these choices is wrong, but swapping their objectives produces disappointment.
Jacksonville Market Snapshot: Prices, Rents, and Yield Bands
The Jacksonville MSA spans Duval County (city of Jacksonville proper), adjacent St. Johns County (Nocatee, St. Augustine corridor), Clay County (Orange Park, Fleming Island), and Nassau County (Yulee, Amelia Island fringe). Investors should think in counties and corridors, not just “Jacksonville” as a single price point.
Duval County remains the core jacksonville investment property market for LTR cash flow. St. Johns County trades at a premium for A-rated schools and master-planned amenities, lower gross yield, stronger tenant quality and resale liquidity.
| Submarket | Property Type | Entry Band | Typical LTR Rent | Gross Yield Band |
|---|---|---|---|---|
| Mandarin / Southside | SFH 3-4 BR | $240K-$340K | $1,900-$2,400/mo | 6.5-8% |
| Arlington / Regency | SFH 3 BR | $200K-$280K | $1,700-$2,100/mo | 7-8.5% |
| Westside (NAS corridor) | SFH 3-4 BR | $210K-$290K | $1,750-$2,200/mo | 7-8.5% |
| Riverside / San Marco | SFH or condo | $220K-$380K | $1,800-$2,500/mo | 5.5-7% |
| Downtown / urban core | Condo 1-2 BR | $180K-$320K | $1,400-$2,000/mo | 5-7% |
| Nocatee / St. Johns | SFH 4 BR | $380K-$480K | $2,400-$3,100/mo | 5.5-7% |
| Orange Park / Clay | SFH 3-4 BR | $230K-$320K | $1,850-$2,350/mo | 6.5-8% |
Florida Realtors and local MLS data place Duval County median single-family prices in a band that allows investors to acquire rent-ready stock without the $400,000 floor that Miami-Dade and much of Tampa Bay now impose. Doc stamp tax on the deed runs $0.70 per $100 of consideration, 0.7% of purchase price, on every Florida closing. A $270,000 Arlington acquisition carries approximately $1,890 in documentary stamp taxes at closing, independent of title and attorney fees.
Non-homestead property tax reassessment at purchase is the line item Jacksonville investors most often under-model. A seller’s capped homestead assessment can jump 30-50% when an investor buys at market price. Budget 1.0-1.3% of purchase price annually for Duval investment property tax until you receive the post-sale TRIM notice.
Worked Example: Gross-to-Net LTR Math on a Mandarin Acquisition
A $285,000 Mandarin three-bedroom built in 2005 grosses $26,400 a year at $2,200 a month, and after 5% vacancy of $1,320, 9% management of $2,376, tax of $3,420, wind insurance of $2,400, and a 1% reserve of $2,850, net operating income is $14,034, a 4.9% net yield on cost against a 9.3% gross yield.
Jacksonville rewards investors who model net yield before offer, not after the property manager sends the first maintenance invoice.
Acquisition assumptions: $285,000 purchase, three-bedroom single-family home in Mandarin, 1,650 sq ft, built 2005, inland flood zone X, no HOA.
| Line Item | Annual Amount | Notes |
|---|---|---|
| Gross rent | $26,400 | $2,200/mo long-term lease |
| Vacancy reserve (5%) | ($1,320) | Conservative for stable LTR |
| Property management (9%) | ($2,376) | Full-service Duval operator |
| Property tax | ($3,420) | ~1.2% of purchase price |
| Insurance (wind) | ($2,400) | Binding quote required |
| Maintenance / capex reserve | ($2,850) | 1% of value rule |
| Net operating income | $14,034 | Before debt service |
| Net yield on cost | 4.9% | NOI / $285,000 |
| Gross yield on cost | 9.3% | Before expenses |
The example shows why Jacksonville headlines at 6-8% gross but delivers 4-6% net on disciplined underwriting, still among the strongest net LTR profiles in Florida at this price point. Compare the same math framework statewide in our Florida rental yield guide. A $285,000 Tampa acquisition might gross similar rent but costs $30,000-$50,000 more at entry, compressing cash-on-cash unless financed leverage amplifies return.
Investors using leverage should stress-test at current mortgage rates, not 2021 assumptions. Cash buyers often accept 4.5-5.5% net yield as sufficient when the alternative is low-yield fixed income in their home currency, particularly European and Canadian buyers routing through our Florida property for foreign buyers guide.
Best Jacksonville submarkets for LTR investors
Jacksonville submarkets split into five working bands: Mandarin and Southside at $240K-$340K with 6.5-8% gross, Arlington and Regency at $200K-$280K with 7-8.5%, the Westside near NAS Jacksonville at $210K-$290K with 7-8.5%, Riverside and San Marco at $220K-$380K with 5.5-7%, and Nocatee in St. Johns County at $380K-$480K with 5.5-7%. Florida Estate defaults to Mandarin for absentee owners.
Submarket selection determines tenant quality, insurance cost, and renewal probability more than a generic “Jacksonville” label on a listing portal.
Mandarin and Southside attract family tenants prioritising A-rated school zones and suburban amenities. Purchase prices run $240,000-$340,000 for three- and four-bedroom stock. Rents of $1,900-$2,400 per month support gross yields in the 6.5-8% band. This is the default recommendation for absentee owners who want predictable LTR economics.
Arlington and Regency offer lower entry, often $200,000-$280,000 for three-bedroom homes, with gross yields reaching the upper end of the 7-8.5% range. Tenant profile skews workforce and service-sector; property condition varies more than in Mandarin. Inspection diligence matters.
Westside near NAS Jacksonville serves military families with Basic Allowance for Housing-supported rents and frequent turnover that still produces low vacancy when priced correctly. Understand lease assignment norms and proximity to base gates, tenants choose commute time over granite countertops.
Riverside and San Marco target urban professionals who want walkable dining and shorter commutes to downtown employment. Older housing stock means higher near-term capex, roof, plumbing, electrical, but rents support 5.5-7% gross when renovated thoughtfully.
St. Johns County (Nocatee, Julington Creek) sits outside Duval but appears constantly in Jacksonville investor searches. School ratings drive rent premiums: $2,400-$3,100 per month on $380,000-$480,000 acquisitions. Gross yield compresses toward 5.5-7%, but tenant quality and resale liquidity improve. Many portfolio builders buy first in Duval, then upgrade to St. Johns on the second acquisition.
Avoid acquiring in FEMA flood zones V or A without elevation certificates, binding flood quotes, and explicit hybrid-seasonal strategy. Jacksonville’s cash-flow edge lives inland, not on unmodelled riverfront lots marketed as “water access.”
Insurance, Taxes, and the Florida Cost Stack in Jacksonville
Insurance and tax lines separate a 7% gross Jacksonville deal from a 4% net reality. Inland Duval single-family rentals typically quote $1,500-$3,500 per year for wind coverage when the roof is post-2002 and wind mitigation features are documented, while properties near the St. Johns River, Ortega, or coastal Nassau may add $800-$2,500+ annually for flood insurance. Non-homestead property tax resets to the purchase price, so a seller’s capped homestead assessment can jump 30-50% and investors should budget 1.0-1.3% of purchase price annually until the post-sale TRIM notice arrives. On a $285,000 Mandarin three-bedroom, the worked model carries $3,420 of tax and $2,400 of wind insurance against $26,400 of gross rent, leaving net operating income of $14,034 and a 4.9% net yield on cost. Florida Estate treats a written insurance quote as the first number to bind.
Insurance is the variable that separates a 7% gross deal from a 4% net reality, even in Jacksonville, where premiums run lower than coastal South Florida.
Inland Duval single-family rentals typically quote $1,500-$3,500 per year for wind coverage when the roof is post-2002 and wind mitigation features are documented. Properties near the St. Johns River, Ortega, or coastal Nassau may require flood insurance adding $800-$2,500+ annually depending on elevation certificate data.
Property tax on investment homes uses non-homestead rates without the Save Our Homes cap that owner-occupiers enjoy. Budget reassessment at your purchase price, not the seller’s tax bill shown on Zillow.
Florida has no state income tax on rental income, a structural advantage for foreign and out-of-state owners documented in our foreign buyers guide. You still file US federal returns on net rental income; entity structure (LLC versus personal title) affects estate planning and liability, not the absence of Florida state tax itself.
For condo investors in downtown high-rises or Riverside conversions, add HOA fees and SB 4-D compliance review. Our Florida condo safety SB 4-D guide covers milestone inspections and Structural Integrity Reserve Studies, mandatory reading before any three-story-plus purchase, even in a market dominated by single-family rentals.
Regulation: LTR landlord environment vs STR complexity
Duval County and the consolidated City of Jacksonville operate under Florida’s generally landlord-friendly framework: no statewide rent control, relatively straightforward eviction procedures compared with Northeast states, and no Osceola-style STR overlay maze.
Vacation rentals under 30 days require registration and tourist development tax collection in Duval. Most jacksonville investment property LTR investors operating on 12-month leases avoid STR licensing entirely, simplifying compliance relative to Orlando.
HOA rental restrictions remain the practical constraint in condo and townhome communities. Many declarations require minimum lease terms of 30, 60, or 90 days; some cap the percentage of units that may lease concurrently. Always request HOA estoppel and governing documents during due diligence.
If your strategy might pivot to mid-term furnished rental for travelling nurses or corporate relocations, verify both county rules and HOA minimum-stay requirements before closing. For investors whose primary goal is nightly vacation income, Jacksonville is the wrong market, redirect to our Orlando area guide and Florida STR regulations guide where overlay-eligible inventory and management infrastructure exist at scale.
Foreign and out-of-state buyers in Jacksonville
Foreign and out-of-state buyers face the same Florida legal stack in Jacksonville as anywhere else: optional LLC ownership, an ITIN or SSN for tax filing, 15% FIRPTA withholding on sale, and a $60,000 US estate tax exemption for non-citizens against roughly $13.6 million for US citizens in 2026. Florida has no state income tax on rental income, though federal returns still apply to net rent. Cash closings in 30-45 days are standard, and wire instructions must be verified by phone with the title company, never by email. SB 264 deserves explicit attention near NAS Jacksonville and Naval Station Mayport, where certain China-domiciled buyers may face prohibitions on purchases near military installations. Florida Estate recommends confirming the current statute and parcel proximity with a Florida-licensed attorney before binding contract, and keeping the same documentation habits that Midwest and Northeast landlords use when they buy in Duval County from a distance.
Foreign buyers face the same Florida legal stack everywhere: optional LLC ownership, ITIN or SSN for tax filing, 15% FIRPTA withholding on sale, and a $60,000 US estate tax exemption for non-citizens versus roughly $13.6 million for US citizens in 2026.
Jacksonville attracts a growing domestic out-of-state buyer cohort, Midwest and Northeast landlords, who want Florida exposure without Miami price tags or Orlando STR operational intensity. Cash closings in 30-45 days are standard. Wire fraud verification, calling the title company directly, never trusting email instructions, is non-negotiable.
SB 264 nationality restrictions deserve explicit attention given NAS Jacksonville and Naval Station Mayport. Certain China-domiciled buyers may face prohibitions on purchases near military installations. Verify current statute and parcel proximity with a Florida-licensed attorney before binding contract, our Florida property for foreign buyers guide covers the full entity and compliance stack.
Jacksonville does not require a separate legal playbook from Tampa or Orlando, only a different asset filter and yield model. Contrast international liquidity and appreciation dynamics in our Miami area guide when deciding whether cash-flow entry or brand-value preservation fits your portfolio.
Property type selection: sfh vs townhome vs condo
| Property Type | Best For | Jacksonville Pros | Jacksonville Cons |
|---|---|---|---|
| Single-family home | Core LTR cash flow | Highest gross yield; broadest tenant pool | Exterior maintenance; yard upkeep |
| Townhome (PUD) | Absentee owners | Lower exterior maintenance | HOA rental caps possible |
| Urban condo | Professional tenants; lower ticket | Turnkey; downtown/Riverside demand | HOA fees; SB 4-D on older stock |
| St. Johns new build | School-driven tenants | Strong resale; quality tenants | Lower gross yield; higher entry |
For the jacksonville investment property buyer focused on LTR cash flow at entry capital, single-family homes in Mandarin, Arlington, and the Westside remain the default recommendation in 2026. Townhomes in master-planned Duval communities are the second choice for reduced maintenance intensity.
Jacksonville due diligence follows Florida statewide standards with local emphasis on flood zone verification and military-proximity SB 264 review for restricted buyers.
Before offer: Pull FEMA flood zone; run rent comps on matching bedroom count and school zone; check Duval Property Appraiser for assessed value and prior sale history; verify non-homestead tax pro forma at purchase price.
Under contract: General inspection ($350-$550 SFH); wind mitigation inspection if not current; roof age documentation; HVAC age; polybutylene plumbing check on pre-1996 stock; HOA estoppel if applicable; insurance binding quote.
Condo additions: SB 4-D milestone inspection report, SIRS, reserve study, special assessment history, rental restriction certification from association, detailed in our Florida condo safety SB 4-D guide.
Pre-close: Title commitment review; wire instruction verification by phone; final walkthrough; lease-ready punch list if immediate tenant placement planned.
Cross-reference the statewide process in our Florida property investment guide and the document request list in our due diligence materials linked from the best areas guide.
Common mistakes Jacksonville investors make
Chasing riverfront flood-zone yield. Listings along the St. Johns look compelling on gross rent screenshots. Net after flood and wind insurance rarely beats inland Arlington on cash-on-cash return.
Ignoring school district boundaries. A home one mile outside an A-rated zone can rent for $250-$350 less per month, a full yield point on a $270,000 acquisition.
Assuming Orlando STR yield applies to Jacksonville LTR. A 9% gross STR pro forma from Kissimmee does not translate to a standard Duval lease without subtracting management, taxes, and turnover, and without overlay eligibility proof.
Using seller homestead tax bill in net model. Post-sale reassessment can add $800-$1,500 annually to carrying costs.
Skipping HOA rental caps. A “great deal” townhome in a 25% rental-cap community means you may never secure a lease license from the association.
Under-reserving capex on 1990s Arlington stock. Roof, HVAC, and water heater replacement clusters on 20-30 year housing cycles, budget reserves in year one, not year five.
Jacksonville vs other Florida metros: quick positioning
| Metro | vs Jacksonville |
|---|---|
| Miami-Dade | Higher prestige; lower LTR net yield; higher insurance; see Miami |
| Tampa Bay | Higher entry; stronger relocation pipeline; slightly lower gross LTR yield; see Tampa |
| Orlando/Osceola | Higher STR gross yield; heavier regulation; see Orlando |
| Naples | Luxury seasonal; lowest yield; highest coastal insurance |
| Fort Lauderdale | Coastal snowbird; mid-tier yield; Broward insurance load |
Jacksonville occupies the entry corner of Florida’s investor map: better cash flow than Miami, lower purchase price than Tampa, simpler operations than Orlando STR, and insurance costs that preserve margin when you stay inland.
What to Verify Before You Close
Use this closing verification checklist for any Jacksonville LTR acquisition:
- Written insurance quote matches pro forma: wind, flood if required, liability.
- Non-homestead property tax calculated at purchase price, not seller’s capped homestead.
- HOA estoppel confirms no pending special assessment and no rental restriction conflict.
- Flood zone documented: elevation certificate on file if riverfront or low-lying.
- Lease market comp supports rent assumption at stated bedroom count and school zone.
- Property management engaged or identified: 8-10% LTR fee in net model.
- Title commitment clear of unexpected liens; survey reviewed for encroachments.
- Wire instructions verified by phone with title company.
- SB 264 proximity review completed if buyer is subject to nationality restrictions near military sites.
- Gross-to-net model reviewed against Florida rental yield guide benchmarks: not listing-agent gross yield alone.
Related guides
- Florida Property Investment Guide, statewide ownership framework
- Florida Rental Yield Guide, gross-to-net math by strategy
- Best Areas to Invest in Florida 2026, eight-metro comparison
- Florida Property for Foreign Buyers, entity, FIRPTA, estate tax
- Florida Condo Safety SB 4-D Guide, milestone inspections, SIRS
- Florida STR Regulations, when STR is and is not viable
- Orlando Vacation Rental Investment Guide, contrast STR market
- Miami Area Guide, appreciation and international liquidity contrast
- Tampa Bay Area Guide, balanced LTR alternative
- Orlando Area Guide, STR yield contrast market
Commercial shortlist and building reviews
Request a curated shortlist on our invest in Miami page, filtered for net yield, HOA rental rules, and SB 4-D document status.
Building reviews in this market:
STR regulation cross-links
Verify county and city short-term rental rules before underwriting yield on this submarket:
Pair county guides with the Florida STR regulations hub and DBPR vacation rental license checklist.
Florida Estate’s insider tip
Insider tip: Re-run the net yield with property tax reset to your purchase price and a written insurance quote before you offer. Post-sale reassessment can add $800-$1,500 a year to carrying costs, and inland wind quotes of $1,500-$3,500 decide whether a $285,000 Mandarin home really holds its 4.9% net yield on cost.
Frequently Asked Questions
Jacksonville is Florida's strongest cash-flow entry market for LTR investors in 2026. Entry prices of $200,000-$400,000, gross LTR yields of 6-8%, inland insurance often $1,500-$3,500/yr, and low regulation friction make it ideal for portfolio builders prioritizing monthly NOI. Net yields of 4-6% are achievable on well-underwritten inland acquisitions.
Gross long-term rental yields typically run 6-8% on suburban single-family homes. Urban condos near downtown and San Marco often yield 5-7% gross. Net yield is usually 1.5-2.5 percentage points below gross after management, tax, insurance, HOA, and vacancy.
Jacksonville generally beats Tampa on headline gross LTR yield and entry price. Tampa wins on corporate relocation depth, appreciation tailwinds, and professional-tenant density. Jacksonville suits maximum cash-on-cash at minimum capital; Tampa suits balanced cash flow with stronger metro growth.
Mandarin, Arlington, Southside, Westside near NAS Jacksonville, and Riverside/San Marco lead for LTR in 2026. St. Johns County suits school-driven tenants at higher entry. Avoid unmodelled flood zones without binding insurance quotes.
Inland Duval SFH rentals typically run $1,500-$3,500/yr. Riverfront and coastal fringe properties can reach $3,500-$6,000+/yr with mandatory flood coverage. Binding quotes before offer are essential.
Yes, no general foreign ownership restriction in Florida. LLC ownership is common for estate planning. FIRPTA 15% withholding applies on sale. SB 264 may restrict certain China-domiciled buyers near military sites, verify with a Florida attorney given NAS Jacksonville proximity.
Orlando leads on gross STR yield in overlay communities at 6-10% gross with heavier regulation. Jacksonville delivers similar headline gross on simpler LTR economics: one tenant, one lease, lower management intensity. Orlando suits STR operators; Jacksonville suits traditional landlords at lower entry.
Three- and four-bedroom single-family homes in suburban Duval dominate. Townhomes offer lower maintenance. Condos work in urban submarkets with mandatory HOA rental review and SB 4-D diligence on three-story-plus buildings.
Get Jacksonville LTR investment options
Share your budget, target submarket, and timeline, we respond within one business day with Duval and St. Johns County properties matched to your cash-flow criteria.