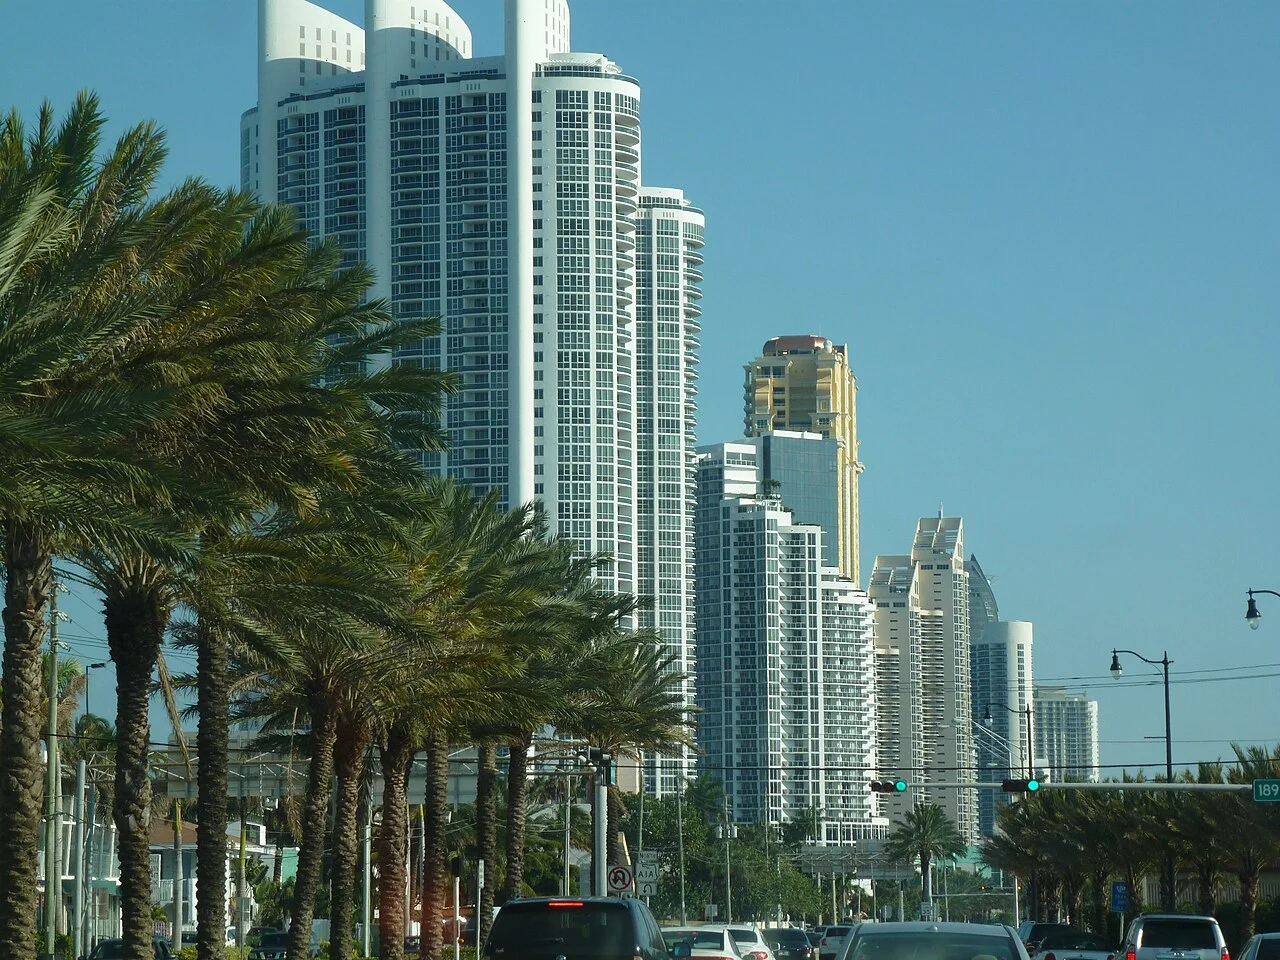
Quick answer: Sunny Isles Beach is Miami-Dade’s luxury beachfront condo strip for international buyers who want tower living on the sand, not Brickell’s finance district. Expect $500K-$2M+ entry on Collins Avenue, 3-4.5% gross yields, seasonal rental as the default strategy, and SB 4-D diligence on every building. Cash and absentee ownership dominate; model net yield before you chase the view.
Sunny Isles Beach sits on a narrow barrier island in northern Miami-Dade County, roughly thirty minutes north of Brickell and twenty minutes south of Fort Lauderdale-Hollywood International Airport. For international buyers comparing Florida’s coastal markets, Sunny Isles luxury condos offer a distinct proposition: wide beach frontage, glass towers with resort amenities, and a buyer pool that has been global for decades before Miami-Dade’s recent Latin American surge.
South Florida absorbed approximately $4.4 billion in foreign capital in 2025, up 42% year on year. Florida captured 21% of all US foreign buyer purchases nationally. Sunny Isles sits inside that flow as a beachfront alternative to urban Miami core districts, less walk-to-office density than Brickell, more sand, pool deck, and family-oriented floor plans. The investment case is not maximum rental yield. It is dollar-denominated coastal real estate with seasonal income optionality and resale liquidity to other international owner-occupiers.
This guide covers Sunny Isles Beach specifically as a Miami-Dade submarket deep-dive for international luxury condo buyers, read the metro-wide Miami Investment Area Guide and the Brickell financial-district guide for broader context before narrowing here. Below: 2026 price bands by tower tier, buyer nationality patterns, seasonal versus long-term rental strategy, SB 4-D and insurance costs on oceanfront associations, comparisons with Miami Beach and Brickell, three worked net scenarios, and the document checklist to run before wire. For foreign buyer mechanics across Miami-Dade, start with the Miami Foreign Buyer Guide. For statewide legal and tax framing, see Florida Property for Foreign Buyers. For gross-to-net math, use the Florida Rental Yield Guide.
Disclaimer: Florida Estate publishes independent research, not legal or tax advice. Yields are illustrative ranges, not guarantees. Consult a Florida-licensed attorney, CPA, and broker before binding decisions.
Luxury Condos market snapshot: q1 2026
Sunny Isles Beach entered 2026 inside the broader Miami-Dade buyer’s market reset. Countywide median condo prices near $640,000 with approximately 17 months of supply give purchasers negotiating leverage that did not exist at the 2022 peak. Sunny Isles pricing does not mirror the county median, the submarket skews luxury and beachfront, but the macro dynamic applies: sellers negotiate on units with assessment risk, developers offer incentives on remaining new inventory, and cash buyers hold the strongest hand.
The core investment entry band for Sunny Isles luxury condos runs $500,000-$1.2 million for two- and three-bedroom units in established Collins Avenue towers. One-bedroom units start lower but carry thinner resale depth for international families. Trophy branded residences, Porsche Design Tower, Mansions at Acqualina, Ritz-Carlton Sunny Isles, sit outside yield math for most investors and function as lifestyle or capital-preservation purchases above $2 million.
Gross rental yield bands on Sunny Isles beachfront condos typically reach 3-4.5% on long-term leases and 3.5-5% effective gross on well-managed seasonal furnished programs that capture winter snowbird premiums. Net yields after non-homestead property tax, HOA, insurance, and management commonly land 1.5-3% on oceanfront towers, comparable to Brickell and Edgewater, with higher absolute carry costs on larger units.
| Metric | Sunny Isles context | International buyer takeaway |
|---|---|---|
| Core entry band | $500K-$1.2M (2-3 BR) | Cash or 30%+ down typical |
| Trophy / branded band | $2M-$10M+ | Lifestyle; not yield-focused |
| Gross LTR yield | 3-4.5% | Seasonal can beat LTR gross |
| Net yield (typical) | 1.5-3% | Model HOA at $1K-$2.5K/mo |
| Foreign capital (South FL 2025) | $4.4B regional inflow | Structural international demand |
| STR feasibility | Low in most towers | Seasonal furnished more viable |
| SB 4-D exposure | Real on 1990s-2000s stock | Document review mandatory |
For metro ranking context across Florida, see Best Areas to Invest in Florida 2026. Sunny Isles fits the appreciation-plus-seasonal-income slot in the Miami-Dade map, not Orlando STR cash flow, not Jacksonville workforce yield.
Why International Buyers Choose Over Miami Beach
International purchasers often arrive with a shortlist: Brickell for urban finance exposure, Edgewater for bay views, Miami Beach for brand recognition, Sunny Isles for beach width and tower amenities. Sunny Isles wins when the buyer prioritizes sand, pool decks, concierge service, and larger interior square footage over South Beach nightlife and Art Deco walkability.
Collins Avenue in Sunny Isles is a corridor of high-rise luxury condos facing the Atlantic. Buildings delivered in the 2000s and 2010s offer modern floor plans, hurricane-rated construction, and amenities, pools, spas, beach service, valet, that match what international buyers expect from Dubai, Tel Aviv, or São Paulo luxury product. Parking is typically structured and deeded, a practical advantage over older Miami Beach stock where parking scarcity erodes daily livability.
Price positioning matters. Sunny Isles trophy units are not cheap, oceanfront luxury is never a discount product, but many buyers find more interior space and newer systems per dollar than in comparable Miami Beach high-rises south of Bal Harbour. The trade-off is neighborhood character: Sunny Isles is residential and beach-focused, not a global nightlife destination. Tenants and resale buyers self-select for that profile.
International buyer concentration also creates resale liquidity. A Venezuelan seller marketing to Argentine and Brazilian buyers is not unusual on Collins Avenue. That cross-border resale depth supports absentee ownership: you are not dependent on a single domestic buyer pool when you exit.
Sunny Isles inventory stratifies sharply by era, brand, floor height, and beach exposure. The table below maps typical 2026 bands for investment-minded international buyers, excluding ultra-trophy outliers that function as collectibles.
| Tier | Price band | Typical product | Buyer profile |
|---|---|---|---|
| Entry luxury | $450K-$650K | 1 BR, 700-950 sq ft, ocean or city view | Single professional, snowbird |
| Core luxury | $600K-$1.0M | 2 BR, 1,100-1,500 sq ft, direct ocean | LATAM family, seasonal owner |
| Premium luxury | $1.0M-$2.0M | 2-3 BR, corner unit, high floor | Cash lifestyle plus seasonal rent |
| Branded / trophy | $2.0M-$10M+ | Porsche, Acqualina, Ritz residences | Capital preservation, not yield |
Entry luxury towers often built in the late 1990s or early 2000s can offer attractive per-square-foot pricing, and the highest SB 4-D assessment risk if reserves were underfunded for decades. Core luxury is the workhorse band for sunny isles luxury condos investment: two-bedroom units that rent to winter seasonal tenants or annual leases to international professionals relocated to Miami-Dade.
Premium luxury units make sense when the buyer accepts lower yield on larger carry and bets on continued international demand for beachfront square footage. Branded residences trade on developer name and amenity spectacle; underwriting should treat rental income as secondary.
Notable Collins Avenue addresses investors cross-shop include Turnberry Ocean Colony, Trump International Sonesta (note political branding sensitivity in some buyer pools), Chateau Beach, Jade Ocean, and newer deliveries along the central beach strip. Always underwrite the building, reserve health, rental rules, master insurance, not the marketing render alone.
International buyer profile: who is buying in 2026 for Luxury Condos
Sunny Isles earned nicknames like “Little Moscow” and “Little Tel Aviv” because Israeli and Russian-speaking buyers built the market’s international identity in the 1990s and 2000s. That history still shows in ownership patterns, broker language capability, and kosher-adjacent retail along Collins Avenue, but 2026 demand is materially broader.
Latin American buyers, Venezuelan, Argentine, Brazilian, Colombian, increasingly treat Sunny Isles as a beachfront alternative to Brickell when family size and school proximity matter more than walking to a trading desk. Canadian and Northeast US buyers dominate seasonal snowbird ownership: own November through April, rent or leave vacant in summer, or flip to long-term lease if HOA permits.
European and Middle Eastern buyers appear in trophy towers and pre-construction launches, often paying cash and holding through LLC structures recommended in the Miami Foreign Buyer Guide. Florida Realtors reported 67% of Florida foreign purchasers were abroad at the time of purchase versus 44% nationally, Sunny Isles fits absentee ownership patterns precisely.
| Buyer origin | Typical motivation | Unit preference | Payment style |
|---|---|---|---|
| Venezuela / Argentina | Dollar hedge, Miami exposure | 2-3 BR ocean | Cash common |
| Brazil / Colombia | Lifestyle plus rental | 2 BR core luxury | Cash or foreign mortgage |
| Israel / Eastern Europe | Beach second home | 2-3 BR, high floor | Cash |
| Canada / US Northeast | Snowbird seasonal | 1-2 BR | Cash or domestic finance |
| Pre-con foreign buyer | Off-plan appreciation | New delivery | Staged USD deposits |
Roughly 47% of Florida foreign buyers pay cash nationally; Sunny Isles skews higher. Pre-construction sales in northern Miami-Dade continue to report foreign participation near 52% of new-development volume in recent South Florida reporting windows, Sunny Isles new towers participate in that share.
Rental strategy: seasonal furnished vs long-term vs STR for Luxury Condos
Sunny Isles is not an Orlando short-term rental market. It is a seasonal furnished and long-term market for most condo investors. HOA declarations on Collins Avenue typically allow annual leases and many permit furnished stays of three months or longer, aligning with snowbird demand, while prohibiting nightly transient occupancy.
Long-term unfurnished (12-month lease): Gross yields near 3-4% on a $750,000 two-bedroom. Lower turnover, lower management intensity, stable professional tenants from Miami-Dade employment base. Best for absentee owners who want predictable operations.
Seasonal furnished (3-6 months, peak winter): Effective gross can reach 4-5% when November-April rents carry premium over summer. Requires furniture capex ($15,000-$40,000 depending on finish), utility management, and professional turnover. HOA minimum-stay rules often permit this pattern when nightly STR does not.
Short-term / Airbnb-style: Blocked or impractical in most Sunny Isles luxury towers. Do not model STR income unless the association manager confirms minimum stays under seven days in writing, rare on Collins Avenue.
| Strategy | HOA fit (typical) | Gross yield band | Absentee complexity |
|---|---|---|---|
| Long-term unfurnished | High | 3-4% | Low-medium |
| Seasonal furnished | Medium-high | 3.5-5% effective | Medium-high |
| Short-term nightly | Low | Not reliable | High if allowed |
| Owner use + seasonal rent | High | Varies | Medium |
Statewide STR licensing, DBPR vacation rental rules, and Miami-Dade overlay regulations are summarized in Florida STR Regulations. For Sunny Isles, HOA rules beat county zoning in practice.
Property management for international owners typically runs 8-12% of gross rent on long-term leases and 15-25% on seasonal furnished programs that include turnover and marketing. Budget a US bank account and automatic HOA payment setup, missed assessments trigger lien risk regardless of owner timezone.
Gross vs net yield: three scenarios for Luxury Condos
Sunny Isles net yield sits far below the gross figure on every Collins Avenue listing. On a $750,000 two-bedroom with $3,200 monthly rent, gross yield is 5.1%, yet property tax of $14,000, HOA of $1,400 monthly, HO-6 insurance of $2,500, 10% management at $3,840, and 5% vacancy at $1,920 leave net near zero before capex. A seasonal furnished program on a $680,000 two-bedroom grosses $47,100, about 6.9%, from five winter months at $5,500 and seven summer months at $2,800, but roughly $38,000 of operating costs and $6,000 of annual furnishing amortization leave about $3,100, near 0.5% net. A $1,400,000 three-bedroom renting at $5,500 monthly grosses 4.7% and nets about 0.6%. Florida Estate reads these scenarios as appreciation and lifestyle purchases, with typical net yields of 1.5-3% on oceanfront towers, not as monthly cash flow.
Every Collins Avenue listing quote is gross until proven otherwise. Oceanfront luxury carry costs compress net returns faster than inland Tampa or Jacksonville assets.
Typical deductions from gross rent on a Sunny Isles long-term or seasonal condo:
- Non-homestead Miami-Dade property tax: roughly 1.8-2.2% of assessed value annually
- HOA: $800-$2,500+ monthly on luxury beachfront towers (amenities, reserves, master insurance pass-through)
- HO-6 interior insurance: $1,500-$4,000 per year
- Property management: 8-12% LTR; higher seasonal
- Vacancy and turnover: 5-10% LTR; 10-15% seasonal
- Special assessments: episodic but material post-SB 4-D
Scenario A: Core luxury long-term
| Line item | Assumption |
|---|---|
| Purchase price | $750,000 (2 BR ocean view) |
| Monthly rent | $3,200 ($38,400/year) |
| Gross yield | 5.1% |
| Property tax | $14,000/year |
| HOA | $1,400/month ($16,800/year) |
| Insurance (HO-6) | $2,500/year |
| Management (10%) | $3,840/year |
| Vacancy (5%) | $1,920/year |
| Net before assessment | ~$0/year (~0% net) |
At $750,000 with $3,200 rent, gross looks acceptable, net near breakeven before capex. This is typical Sunny Isles math: appreciation and lifestyle, not monthly cash flow.
Scenario B: Seasonal furnished (snowbird peak)
| Line item | Assumption |
|---|---|
| Purchase price | $680,000 (2 BR) |
| Seasonal rent (5 mo @ $5,500) | $27,500 |
| Summer LTR (7 mo @ $2,800) | $19,600 |
| Total annual gross | $47,100 (~6.9% gross) |
| Operating costs (tax, HOA, ins, mgmt) | ~$38,000 |
| Furnishing amortized (5 yr) | $6,000/year |
| Net approximate | ~$3,100 (~0.5% net) |
Seasonal strategy improves gross meaningfully; net still thin unless purchase price negotiates lower.
Scenario C: Premium hold (low yield acceptance)
| Line item | Assumption |
|---|---|
| Purchase price | $1,400,000 (3 BR high floor) |
| Monthly rent | $5,500 ($66,000/year) |
| Gross yield | 4.7% |
| Total operating costs | ~$58,000/year |
| Net approximate | ~$8,000 (~0.6% net) |
Premium units attract tenants but scale costs rise with square footage and HOA tier.
For statewide yield comparison, see Florida Rental Yield Guide. Sunny Isles belongs in the same net-yield band as Miami coastal condos, not in Central Florida STR territory.
SB 4-d, insurance, and hidden costs on oceanfront towers for Luxury Condos
A Sunny Isles condo is priced by its association as much as by its list price. Florida SB 4-D requires milestone structural inspections and Structural Integrity Reserve Studies on qualifying buildings of three or more stories, and the submarket has dense coastal high-rise stock from the 1990s through the 2010s now cycling through those mandates. Before any offer, investors request the milestone report, the SIRS, the reserve funding percentage, special assessment history, 24 months of board minutes, and the master insurance certificate. A $900,000 list price with a pending $120,000 assessment is not a $900,000 asset. Carry costs add up quickly: non-homestead Miami-Dade tax of roughly 1.8-2.2% of assessed value, HOA of $800-$2,500+ monthly, and HO-6 insurance of $1,500-$4,000 per year. Florida Estate treats master policy renewal status as a separate check, because coastal repricing since 2022-2024 affects every Collins Avenue tower regardless of the unit quote.
Florida SB 4-D, expanded after the 2021 Surfside collapse, requires milestone structural inspections and Structural Integrity Reserve Studies on qualifying condominium buildings. Sunny Isles has dense coastal high-rise stock from the 1990s through 2010s now cycling through inspection and reserve funding mandates.
Before any offer on sunny isles luxury condos, request:
- Latest milestone inspection report and engineer letter
- Structural Integrity Reserve Study (SIRS)
- Reserve funding percentage versus study recommendation
- Special assessment history and pending votes
- 24 months of board minutes mentioning structural or reserve topics
- Master insurance certificate and any wind or flood premium increases
A $900,000 list price with a pending $120,000 assessment is not a $900,000 asset. International buyers absentee-managed face the highest surprise risk because they are not in the elevator hearing neighbor gossip about the upcoming vote.
Insurance stacks in layers: master policy via HOA (wind and flood often embedded or separately billed), HO-6 for interior and contents, and potential post-hurricane special levies if deductibles hit association balance sheets. Coastal repricing since 2022-2024 affects every Collins Avenue tower, verify master policy renewal status, not just your unit quote.
Full SB 4-D checklist: Florida Condo SB 4-D Guide. Insurance line items: Florida Property Insurance Investment Costs 2026.
Foreign Buyer Mechanics: Closing Remotely
International purchasers follow the same Miami-Dade closing pipeline as Brickell buyers with additional tax and entity planning.
Entity structure: Many foreign nationals hold through Florida LLCs owned by foreign entities or trusts. US estate tax exposure for non-residents uses only a $60,000 federal exemption on US-situs assets, a critical planning gap for a $800,000 Sunny Isles condo. Align structure with a US attorney before signing contract.
FIRPTA: Applies on sale, not purchase. Foreign sellers face 15% gross withholding; buyers must plan withholding obligations if they exit later.
SB 264: Restricts purchases near certain military installations for buyers domiciled in seven named countries (China, Cuba, Venezuela, Syria, Iran, Russia, North Korea). Most LATAM and European buyers are unaffected, verify with counsel.
Financing: Foreign national mortgages typically require 25-30% down, higher interest rates, and DSCR options for rental-backed debt. Cash dominates Sunny Isles luxury transactions.
Remote closing: Sign at consulate or apostille notary; courier originals; wire early; verify wire instructions by phone. Title company and attorney coordinate recording in Miami-Dade.
Deep dive: Miami Foreign Buyer Guide and Florida Property for Foreign Buyers. Due diligence sequence: Due Diligence Florida Real Estate.
Vs Brickell vs Miami beach: decision matrix for Luxury Condos
International buyers rarely choose in isolation, they cross-shop three Miami-Dade addresses.
| Factor | Sunny Isles | Brickell | Miami Beach (South) |
|---|---|---|---|
| Primary appeal | Beachfront tower living | Walk-to-work finance core | Global brand, nightlife |
| Typical 2 BR band | $600K-$1.2M | $650K-$950K | $700K-$1.5M+ |
| Gross yield | 3-4.5% | 3-5% | 2.5-4% |
| Seasonal rental fit | Strong | Weak | Mixed |
| STR feasibility | Low | Low | Low (zoning plus HOA) |
| Floor plan size | Larger typical | Compact urban | Mixed vintage |
| International resale pool | Deep | Deep | Deepest brand |
| SB 4-D risk | High (1990s-2000s) | High (1980s-1990s) | Very high (older stock) |
Choose Sunny Isles when beach, space, and seasonal income matter more than walking to Brickell offices. Choose Brickell when urban tenant depth and finance-sector resale dominate. Choose Miami Beach when brand premium and South Beach lifestyle justify higher carry and older building risk.
Link back to metro overview: Miami Investment Area Guide. Statewide frame: Florida Property Investment Guide.
Who Should Buy in Sunny Isles and Who Should Not
Strong fit: International cash buyers seeking dollar-denominated beachfront real estate with five-to-ten-year hold horizons. Latin American families comparing Miami submarkets on space and sand. Snowbirds who will use the unit winter and rent seasonally summer. Buyers comfortable with HOA governance and SB 4-D document review. Investors pairing a low-yield Sunny Isles asset with higher-cash-flow Florida markets elsewhere in the portfolio.
Weak fit: Yield-first investors needing 6%+ net cash-on-cash, look to Tampa, Jacksonville, or Orlando corridors in Best Areas to Invest in Florida 2026. Buyers who cannot tolerate special assessment risk on 1990s towers. Anyone modeling Airbnb income without written HOA confirmation. Purchasers skipping estate tax and entity planning because they “only” buy one Florida condo.
Run this sequence after identifying a tower and unit:
- Confirm rental minimum stay and furnished rules with HOA management in writing
- Request full SB 4-D package: milestone report, SIRS, reserve study, assessment history
- Review two years of association financials and board minutes
- Obtain HO-6 quote; verify master policy status and wind or flood coverage
- Model net yield with actual Miami-Dade tax, HOA, and 5-10% vacancy
- Confirm cash path or foreign national / DSCR financing pre-approval
- Run title and lien search; confirm no open association claims against unit
- Align LLC, trust, or entity structure and estate plan with US attorney
- Compare against Brickell and Miami alternatives on net basis
- Verify remote closing timeline with title company (30-45 days cash typical)
Never wire funds without verbal confirmation of instructions. Fraud targeting international buyers spikes around closing week.
Closing Verification: Re-Check Before Wire
Within seven days of closing, re-verify:
- No new special assessment vote scheduled between contract and closing
- Master insurance certificate current through closing date
- HOA estoppel matches expected fees; no unpaid unit assessments
- Seller credits for known SB 4-D items appear on closing statement
- Rental rules unchanged since contract date
Florida Estate research is editorial, not a substitute for licensed professional advice on your specific unit, tax residency, and association.
Luxury Condos commercial shortlist and building reviews
Request a curated shortlist on our invest in Miami page, filtered for net yield, HOA rental rules, and SB 4-D document status.
Building reviews in this market:
Luxury Condos STR regulation cross-links
Verify county and city short-term rental rules before underwriting yield on this submarket:
Pair county guides with the Florida STR regulations hub and DBPR vacation rental license checklist.
Florida Estate’s insider tip
Insider tip: Ask for the milestone report, the latest SIRS, the reserve funding percentage and 24 months of board minutes before pricing any Sunny Isles tower. With HOA at $800-$2,500+ a month, a pending six-figure assessment can erase years of a 3-4.5% gross yield.
Frequently Asked Questions
Sunny Isles Beach suits international buyers who want Atlantic beachfront towers, newer luxury stock, and seasonal furnished rental income without Miami Beach price friction. Entry for investment-grade two-bedroom units runs roughly $500,000-$900,000 in 2026, with trophy buildings exceeding $2 million. Gross yields typically run 3-4.5% on long-term or seasonal leases. Net yields after HOA, insurance, and non-homestead tax often land 1.5-3%. The buyer profile skews cash-heavy and absentee, plan for professional management and SB 4-D document review on every tower.
One-bedroom beachfront units start near $450,000-$650,000 in mid-tier towers. Two-bedroom luxury units on Collins Avenue commonly trade $600,000-$1.2 million. Three-bedroom and penthouse inventory in branded residences such as Porsche Design Tower or Mansions at Acqualina can exceed $2 million-$10 million. Pre-construction deposits in new Sunny Isles launches often follow 30-50% staged schedules over two to three years, with foreign nationals representing a large share of off-plan sales.
Sunny Isles has long attracted Israeli, Russian, and Eastern European buyers alongside Canadian and Northeast US snowbirds. In 2026 the mix has broadened: Venezuelan, Argentine, Brazilian, and Colombian purchasers increasingly cross-shop Sunny Isles against Brickell and Edgewater. Florida overall recorded 16,401 international transactions totaling $10.4 billion in the twelve months through mid-2025. Sunny Isles benefits from overflow demand from buyers who want beachfront exposure without South Beach parking and zoning friction.
Seasonal furnished rentals of three to six months align better with Sunny Isles HOA rules than nightly Airbnb income. Many Collins Avenue associations permit annual leases and seasonal furnished stays but prohibit transient hotel-style occupancy. Gross effective yields can improve when winter snowbird demand peaks November through April, but budget furnishing capex, utilities, turnover, and 10-15% vacancy between seasons. Request minimum-stay rules in writing from the association manager before purchase.
Sunny Isles generally offers newer high-rise inventory, wider beachfront frontage, and lower friction than Miami Beach for parking and daily living, at a discount to South Beach trophy pricing on a per-bedroom basis. Miami Beach commands stronger international brand premium and nightlife adjacency. Sunny Isles wins for family-oriented beach living, larger floor plans, and towers delivered after 2000 with modern amenities. Gross yields are comparable at 3-4.5%, but insurance and HOA on oceanfront towers compress net returns in both markets.
Florida SB 4-D requires milestone structural inspections and Structural Integrity Reserve Studies on condominium buildings three or more stories. Sunny Isles has substantial 1990s and 2000s coastal stock now entering inspection cycles alongside newer compliant towers. Before buying, request the milestone report, latest SIRS, reserve funding percentage, pending special assessments, and 24 months of board minutes. A luxury list price means little if the association is levying a six-figure assessment per unit.
No. Remote closings are standard for foreign nationals purchasing Sunny Isles condos. Documents are typically signed through a US consulate or apostille-certified notary abroad, with originals couriered to the Florida title company. Wire transfers should arrive three to five business days before closing, and wiring instructions must be verified by phone, never by email alone. A Florida real estate attorney can represent absentee buyers through the entire process.
Budget non-homestead property tax at roughly 1.8-2.2% of assessed value in Miami-Dade, HOA fees of $800-$2,500+ monthly on luxury beachfront towers, HO-6 interior insurance of $1,500-$4,000 per year, and potential wind or flood pass-throughs via the master policy. Property management runs 8-12% for long-term leases and higher for seasonal furnished programs. Oceanfront buildings with full-service amenities and valet parking sit at the top of the carry-cost range.
Get Sunny Isles luxury condo options
Share your budget, nationality, rental strategy, and timeline, we respond within one business day with Collins Avenue towers that match your SB 4-D and HOA requirements.
Buildings we cover in Sunny Isles
2 buildings, listed by entry price. Entry starts at $1,150,000. Each card carries dues, letting rules and the milestone inspection position.
| Building | Neighbourhood | Built | From |
|---|---|---|---|
| Echo Aventura Condos | Aventura | n/a | $1,150,000 |
| Trump Palace Condos Sunny Isles Beach | Sunny Isles Beach | n/a | $1,250,000 |