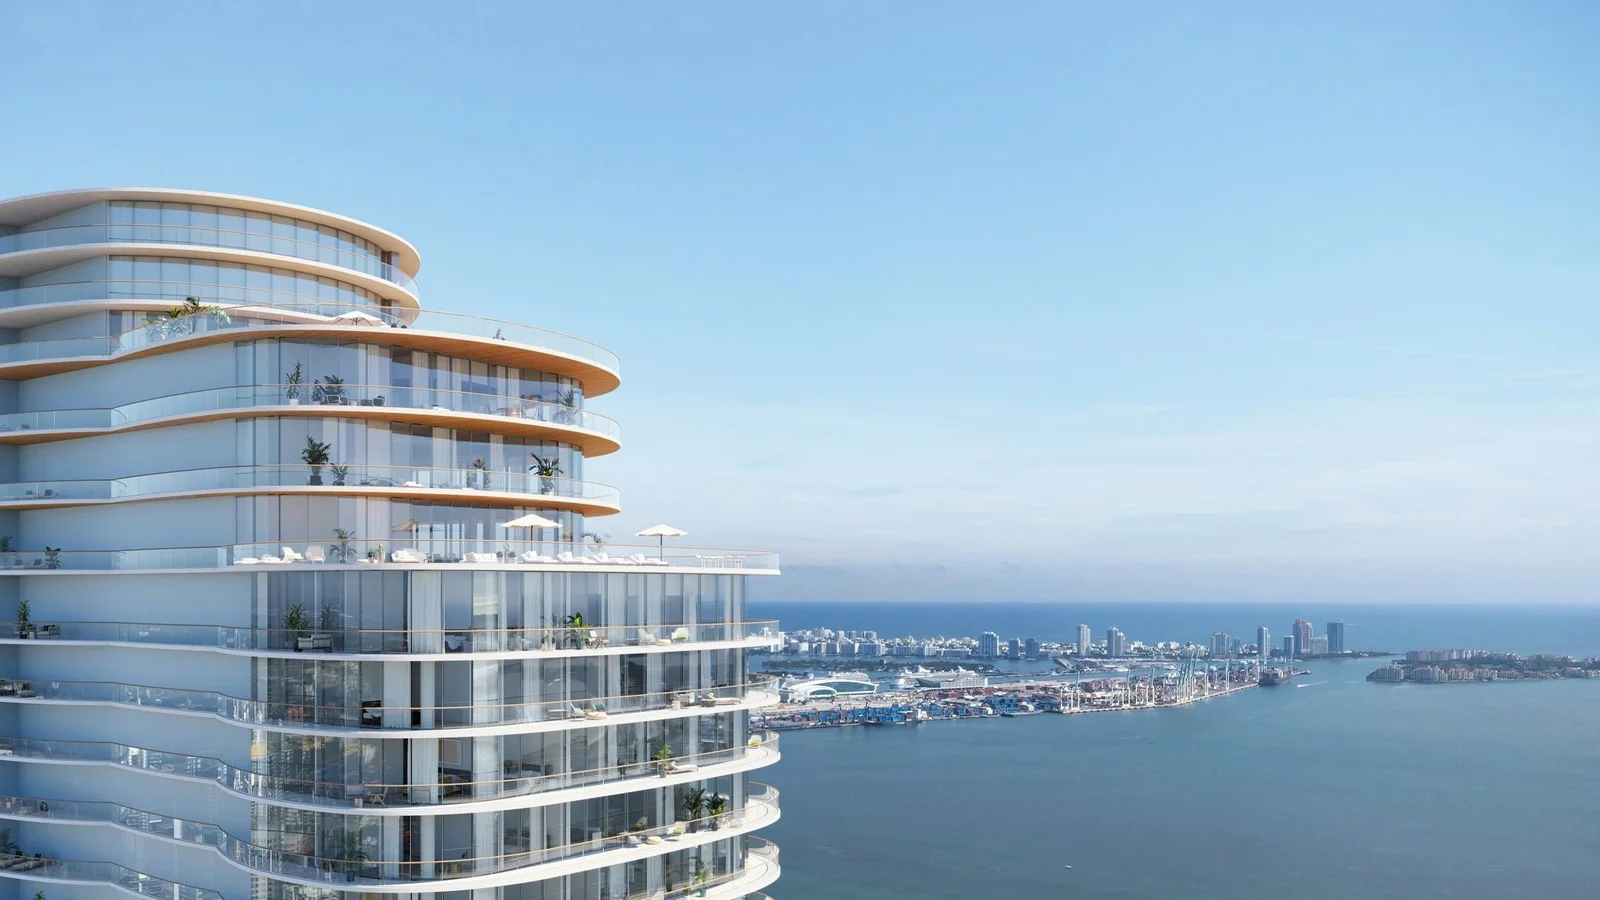
Quick answer: Cipriani Residences Miami is the highest price-per-square-foot pre-construction in Brickell at $1,500-$2,000/sqft. Projected net yields of 1.1-2.5% reflect the branded premium. SB 4-D exempt for 25 years. This is a capital appreciation and lifestyle play, not an income investment. The Cipriani brand commands resale premiums, but only if Miami luxury continues its upward trajectory through delivery.
Cipriani Residences Miami will rise at 1420 South Miami Avenue in the heart of Brickell, on a 2.6-acre waterfront site with direct Biscayne Bay access. Developed by Mast Capital in partnership with the Cipriani family, operators of Harry’s Bar in Venice, the Cipriani restaurant chain, and luxury hospitality properties in New York, London, and Abu Dhabi, the 80-story tower will contain approximately 397 residences with Cipriani-branded restaurant, bar, pool club, and spa services available to owners.
For investors, Cipriani Residences represents the extreme end of the Brickell pre-construction spectrum: maximum brand premium, maximum price per square foot, maximum capital commitment, and minimum expected current yield. The investment thesis is entirely predicated on capital appreciation powered by the Cipriani brand’s ability to sustain premium pricing on resale, a phenomenon well-documented in branded residences globally but largely untested in Brickell specifically.
This review models projected yields honestly (they are low), assesses the branded residence premium through international comparables, explains what the Cipriani brand does and does not provide to unit owners, and frames the decision as a risk-return tradeoff that requires specific investor circumstances to justify.
For broader Brickell investment context, see our Brickell area guide. For the Miami market overview, read the Miami area analysis.
Project specifications
| Specification | Detail |
|---|---|
| Address | 1420 South Miami Avenue, Miami |
| Developer | Mast Capital (Camilo Miguel Jr.) |
| Brand partner | Cipriani (Italian hospitality family) |
| Architect | Arquitectonica |
| Stories | 80 |
| Residences | ~397 |
| Unit sizes | 1,100-6,000+ sq ft |
| Construction status | Under construction (mid-2026) |
| Projected delivery | 2028-2029 |
| Price range | $1.5M-$15M+ |
| Price per sq ft | $1,500-$2,000+ |
| Site | 2.6 acres waterfront with private marina basin |
| Branded amenities | Cipriani restaurant, bar, pool club, spa, private dining rooms |
| Parking | Automated robotic parking system |
The 397-unit count is substantially higher than 1428 Brickell (189 units) but the site’s 2.6 acres provide more generous common spaces. The automated parking system eliminates traditional parking ramps, recovering floor area for amenity spaces but introducing mechanical complexity that will affect long-term HOA costs.
Pricing context: the branded residence premium
Understanding why Cipriani commands $1,500-$2,000/sqft when competing Brickell towers sell at $1,100-$1,400 requires understanding the branded residence market globally.
| Market | Branded residence premium vs non-branded | Source |
|---|---|---|
| Global average | 25-35% | Knight Frank Branded Residences Report 2024 |
| Miami (existing brands) | 20-40% | Ritz-Carlton, Four Seasons, Faena comparables |
| Dubai | 30-50% | Highest premium market globally |
| London | 20-30% | One Hyde Park, Bulgari |
| New York | 15-25% | Aman, Mandarin Oriental |
Cipriani’s specific brand positioning:
Cipriani occupies a niche between lifestyle hospitality (Soho House) and ultra-luxury hotel brands (Four Seasons, Aman). The brand’s strength is food and beverage culture, social dining, and Italian aesthetic rather than hotel operations or property management. This positions Cipriani Residences Miami as a lifestyle branded product rather than a hotel-services branded product.
What this means for investors:
The premium is real on resale, branded residences consistently outperform non-branded neighbors. But the premium requires the brand to maintain relevance and operational quality over your hold period. Cipriani’s Venice origins and 90+ year heritage suggest stability, but their track record in US residential development is not yet established.
Projected net rental yield: three scenarios
These projections are highly speculative. The building has not delivered, operating costs are not established, and the rental market in 2028-2029 cannot be predicted with confidence. Models are provided to frame the income component of what is primarily a capital appreciation investment.
Assumptions: One-bedroom + den (1,300 sq ft), $1,350,000 purchase price (mid-range current pricing), delivery 2029. Luxury Brickell one-bedrooms in the $1M+ segment currently achieve $4,000-$5,500/month; the Cipriani brand may command a 10-15% rental premium.
| Cost line | Conservative | Base case | Optimistic |
|---|---|---|---|
| Monthly rent | $4,500 | $5,200 | $6,000 |
| Annual gross rent | $54,000 | $62,400 | $72,000 |
| Vacancy (10% / 6% / 3%) | −$5,400 | −$3,744 | −$2,160 |
| Effective gross income | $48,600 | $58,656 | $69,840 |
| Property management (8%) | −$3,888 | −$4,692 | −$5,587 |
| Property tax (non-homestead ~1.1%) | −$14,850 | −$14,850 | −$14,850 |
| Insurance (HO-6 + wind) | −$3,800 | −$3,400 | −$3,000 |
| HOA fees (est. $1,100/mo) | −$13,200 | −$13,200 | −$13,200 |
| Capex reserve (3%) | −$1,458 | −$1,760 | −$2,095 |
| Projected Net Operating Income | $11,404 | $20,754 | $31,108 |
| Projected net yield on $1,350,000 | 0.8% | 1.5% | 2.3% |
Adjusted for self-managed experienced investor with premium positioning:
| Cost line | Conservative | Base case | Optimistic |
|---|---|---|---|
| Monthly rent | $4,800 | $5,500 | $6,200 |
| Annual gross rent | $57,600 | $66,000 | $74,400 |
| Vacancy (8% / 4% / 2%) | −$4,608 | −$2,640 | −$1,488 |
| Effective gross income | $52,992 | $63,360 | $72,912 |
| Property management (self/4%) | −$2,120 | −$2,534 | −$2,916 |
| Property tax (~1.1%) | −$14,850 | −$14,850 | −$14,850 |
| Insurance (HO-6) | −$3,200 | −$2,800 | −$2,600 |
| HOA fees ($1,100/mo) | −$13,200 | −$13,200 | −$13,200 |
| Capex reserve (2%) | −$1,060 | −$1,267 | −$1,458 |
| Projected Net Operating Income | $18,562 | $28,709 | $37,888 |
| Projected net yield on $1,350,000 | 1.4% | 2.1% | 2.8% |
Even in the optimistic self-managed scenario, net yield barely exceeds the risk-free rate available from US Treasury bonds. The investment case for Cipriani Residences is capital appreciation or personal use, not income generation.
SB 4-d: complete exemption
As new construction, Cipriani Residences Miami will be exempt from all SB 4-D milestone inspection requirements for 25 years from the certificate of occupancy (approximately 2053-2054). This means:
| SB 4-D item | Cipriani status |
|---|---|
| Milestone inspection requirement | None until ~2053-2054 |
| SIRS reserve funding pressure | Minimal (all new systems) |
| Special assessment risk (structural) | Near zero for 20+ years |
| HOA fee pressure from compliance | None |
This exemption is identical to competing new-construction projects (1428 Brickell, Six Senses). It does not provide a competitive advantage within the pre-construction segment but is a meaningful advantage over established buildings where SB 4-D compliance is an active and expensive process.
For the complete SB 4-D investment framework, see our Florida condo safety guide.
HOA rental restrictions: expected framework
The condominium declaration for Cipriani Residences has not been publicly recorded. Based on the luxury positioning, brand partnership structure, and Miami-Dade market norms, the following rental framework is expected:
Expected rental rules:
- Minimum lease term: likely 6 months or 12 months (luxury brands typically prefer longer minimums)
- Short-term rental: expected to be prohibited
- Platform rental (Airbnb): expected to be prohibited
- Cipriani hotel program for residential units: not expected (Cipriani provides amenity services, not hotel rental operations)
- First-year rental restriction: possible 12-month owner-occupancy requirement
The Cipriani brand confusion:
Many buyers assume that purchasing a Cipriani-branded residence provides access to a hotel-style rental program managed by the Cipriani brand. Based on available information, this is not the case. The Cipriani partnership provides:
- Restaurant and bar operations within the building
- Pool club and spa managed to Cipriani standards
- Branded aesthetic and design language
- Event and private dining services
It does not provide:
- Hotel rental management of your individual unit
- Short-term rental rights or platform listing services
- Revenue-sharing from building F&B operations
- Guaranteed rental income or occupancy programs
Investor implication: You will rent your unit through a traditional residential lease to a long-term tenant, exactly as you would at Icon Brickell or Panorama Tower. The Cipriani brand adds tenant appeal and potentially commands a 5-15% rent premium from tenants who value the address and amenities, but it does not fundamentally change the rental strategy.
Developer assessment: mast capital
Unlike 1428 Brickell (Related Group with 40+ year local track record), Cipriani Residences is developed by Mast Capital, a younger firm led by Camilo Miguel Jr. Understanding the developer’s background is critical for pre-construction risk assessment.
| Factor | Mast Capital assessment |
|---|---|
| Firm age | Founded ~2007 |
| Miami residential delivery history | Smaller-scale projects; Cipriani is the flagship |
| Previous notable projects | Casa Bella (Fort Lauderdale), Onda (Aventura) |
| Construction financing | Secured (reduces abandonment risk) |
| Brand partnership | Cipriani family provides design/operations standards but not financial backing for development |
| Site acquisition | Paid premium for 2.6-acre waterfront Brickell site |
Risk assessment:
Mast Capital’s track record is shorter and smaller-scale than Related Group’s. The Cipriani project is an order of magnitude larger and more complex than their previous work. This does not mean failure is likely, many excellent Miami buildings were developed by firms on their way up, but it does mean the execution risk is higher than buying from a developer with 90,000 units of demonstrated capacity.
Mitigating factors:
- Construction financing secured (bank has performed its own underwriting)
- Cipriani brand partnership creates reputational accountability
- Arquitectonica provides design and engineering continuity with proven Brickell execution
- Florida condominium statute protects buyer deposits in escrow regardless of developer outcome
- Construction is actively underway, the highest-risk phase (pre-financing/pre-permits) has passed
Advantages of investing in Cipriani residences
- Branded residence premium of 25-35% on resale provides potential for superior capital appreciation
- Cipriani F&B and lifestyle amenities create genuine tenant and buyer differentiation in Brickell
- 2.6-acre waterfront site with private marina basin, largest site among competing Brickell towers
- 25-year SB 4-D exemption eliminates structural compliance costs for the foreseeable future
- Italian design aesthetic targets Latin American and European buyers who identify with the brand
- 397-unit count provides reasonable liquidity without excessive internal competition
- Waterfront positioning with bay access adds value layer beyond standard Brickell Avenue towers
- Automated parking system maximizes usable residential and amenity space
Main risks
- Highest price per square foot in Brickell ($1,500-$2,000) creates maximum downside exposure in correction
- Projected net yields below 2.5% in most scenarios, below risk-free rate of US Treasury bonds
- Mast Capital has less Miami high-rise delivery history than Related Group or Swire
- Cipriani brand is untested in Florida residential specifically (no local resale premium data yet)
- 50% deposit locked for 3+ years without income on $675,000+ capital commitment
- HOA fees projected at $1,100+/mo will be among the highest in Brickell due to branded amenity operations
- Simultaneous luxury delivery (1428, Six Senses, Baccarat) may split the ultra-luxury tenant pool
- Automated parking system introduces maintenance complexity and potential reliability issues
- No established rental rate data, all yield projections are speculative
- Currency risk and FIRPTA impact magnified on higher-value transaction
- Brand relevance risk: if Cipriani’s US presence does not develop as projected, the premium may not materialize
Branded residence track record: what history says
International branded residence data provides context for Cipriani’s potential performance, though past results do not guarantee future returns.
| Branded project | Location | Year | Premium achieved on resale vs neighborhood |
|---|---|---|---|
| Ritz-Carlton Residences | Sunny Isles | 2012 | +25-30% vs non-branded beachfront |
| Four Seasons Surf Club | Surfside | 2019 | +35-45% vs North Beach comparables |
| Faena House | Mid-Beach | 2015 | +40-50% vs non-branded Mid-Beach |
| St Regis Bal Harbour | Bal Harbour | 2012 | +30-40% vs non-branded Bal Harbour |
| Aman Miami (projected) | Mid-Beach | 2027 | TBD |
The pattern indicates that well-executed branded residences in South Florida consistently achieve premiums on resale. However, the data comes from established hotel brands (Ritz-Carlton, Four Seasons, St Regis) with decades of US residential development experience. Cipriani’s hospitality credentials are strong but their residential development track record is primarily European.
Investment decision framework
Cipriani Residences works for:
Ultra-high-net-worth investors ($5M+ liquid net worth after this purchase) who treat Miami real estate as a portfolio diversification asset rather than an income generator. Buyers who value the Cipriani lifestyle brand and may use the residence personally 4-8 weeks per year while renting the remainder. International buyers from Italy, Latin America, or the Middle East who identify with the Cipriani brand and social culture. Family office capital seeking long-term (10-15 year) appreciation in a trophy asset with brand protection against market downturns.
Cipriani Residences does not work for:
Income-focused investors who need rental yield to justify capital deployment. Buyers with less than $3M liquid net worth who would be over-concentrated in a single asset. Investors with hold periods under 7 years who need appreciation to offset high transaction costs. Anyone who believes the branded premium requires STR income to monetize. Investors who are comparing this to stabilized buildings on a yield basis, the comparison is meaningless because the use cases are fundamentally different.
How does Cipriani vs Competing Branded Residences in Miami?
| Project | Brand type | Price/sqft | Delivery | Target buyer |
|---|---|---|---|---|
| Cipriani Miami | F&B / lifestyle | $1,500-$2,000 | 2028-2029 | Social / European / Latin American |
| Six Senses Brickell | Wellness resort | $1,200-$1,600 | 2028-2029 | Health-conscious UHNW |
| Aman Miami | Ultra-luxury retreat | $3,000-$5,000 | 2027 | Ultra-discreet UHNW |
| Baccarat Miami | Crystal / French luxury | $1,300-$1,800 | 2028 | Design-forward / French aesthetic |
| Ritz-Carlton Residences (new) | Hotel / service | $1,800-$2,500 | Various | Service-dependent buyers |
Cipriani occupies the middle band of branded pricing, below Aman’s ultra-luxury tier but above standard luxury developments. The differentiation is specifically Italian F&B culture and social dining, a narrower brand promise than full-service hotel brands but one with strong appeal to specific demographic segments.
Five-year post-delivery projection
Projection for a $1,350,000 one-bedroom + den, assuming delivery in 2029 and base-case scenario:
| Year | Gross rent | Projected NOI | Cumulative cash | Estimated value (4% appreciation) |
|---|---|---|---|---|
| 2029 | $66,000 | $28,709 | $28,709 | $1,404,000 |
| 2030 | $68,640 | $29,200 | $57,909 | $1,460,160 |
| 2031 | $71,386 | $29,500 | $87,409 | $1,518,566 |
| 2032 | $74,241 | $30,000 | $117,409 | $1,579,309 |
| 2033 | $77,211 | $30,800 | $148,209 | $1,642,481 |
Five-year total: approximately $148,209 cumulative NOI + $292,481 unrealized appreciation = $440,690 gross total return on $1,350,000, or approximately 32.6% cumulative (5.8% annualized). The 4% annual appreciation assumption reflects the branded premium holding stable; if the brand performs below expectations, appreciation may be 2-3% (aligning with general Brickell), reducing total return to 3.5-4.5% annualized.
Note: this projection does not begin until delivery (2029). The 2-3 year deposit period preceding delivery generates zero return while capital is locked.
Tax implications at the Cipriani price point
The higher purchase price at Cipriani amplifies all tax impacts for foreign investors:
| Tax item | Impact at $1,350,000 |
|---|---|
| Non-homestead property tax (~1.1%) | ~$14,850/yr |
| FIRPTA withholding on sale (15% gross) | $202,500 withheld at closing |
| US estate tax exposure (over $60K exemption) | Potentially $500,000+ in estate tax without LLC/trust |
| Documentary stamps on purchase (0.7%) | $9,450 |
| Title insurance | ~$6,000-$8,000 |
The estate tax exposure is particularly severe at this price point. Without proper structuring through a US or international entity, a non-citizen owner’s death could trigger estate tax of 40% on the value above $60,000, approximately $516,000 on a $1,350,000 property. This is a mandatory structuring conversation before purchase, not optional planning.
Florida Estate’s final assessment
Cipriani Residences Miami is a lifestyle and brand appreciation investment, not an income asset. Projected net yields below 2.5% in most scenarios confirm that rental income alone does not justify the capital commitment. The investment thesis requires faith in two propositions: that Miami’s ultra-luxury market continues appreciating at 3-5% annually through 2033, and that the Cipriani brand delivers the 25-35% resale premium that comparable branded residences have achieved in South Florida.
Both propositions are reasonable but unproven for this specific project. The Cipriani brand has no Florida residential track record. Mast Capital is delivering at a scale beyond their previous experience. And the 2027-2029 delivery cycle will bring unprecedented luxury supply to Brickell simultaneously.
The right buyer does not ask “what is the yield?”, they ask “will this be the most desirable address in Brickell in 10 years?” If the answer is yes, the yield is irrelevant because 30-50% appreciation over a decade will dwarf income returns. If the answer is uncertain, more proven alternatives (1428 Brickell, Panorama Tower, or stabilized existing buildings) offer better risk-adjusted returns with immediate income and known costs.
For the yield methodology, see our Florida rental yield guide. For SB 4-D context, read our condo safety guide.
What market context and commercial intake should investors verify
See the Miami area overview for supply, foreign buyer share, and county-wide STR rules.
Want a shortlist that includes this building? Submit budget on invest in Miami.
Compare nearby towers:
What developer due diligence applies
Before you wire pre-con or resale earnest money, read the Mast Capital developer dossier for deposit escrow rules, delivery history, foreign buyer concentration, and sourced red-flag research steps tied to this tower.
Co-developer or partner profiles on overlapping projects:
Pair the developer dossier with the Florida due diligence checklist and SB 4-D condo safety guide when buying Miami-Dade condominiums.
What pre-construction review steps apply
This tower also has a dedicated pre-construction lens covering deposit escrow, delivery timeline, and foreign buyer compliance: Cipriani Residences Miami: Branded Condo pre-con review.
Use the project review for reservation decisions and the building review for stabilized yield, HOA fees, and rental restrictions after certificate of occupancy.
Florida Estate’s insider tip
Insider tip: Do not underwrite Cipriani on rent. The base-case net yield is 1.5% to 2.8% on $1,350,000 while a 50% deposit sits locked for 3+ years. Settle the estate tax question first: without an LLC or trust, a non-citizen owner faces roughly $516,000 of exposure at this price, and a 15% FIRPTA withholding would take $202,500 at resale.
Frequently Asked Questions
Projected net yields range from 1.1% (conservative) to 2.5% (optimistic) on a $1,350,000 one-bedroom. Base case is approximately 1.8%. These are speculative projections since the building has not delivered. Rental income does not justify the investment alone, appreciation is the thesis.
Restaurant and bar services, pool club, spa, event spaces, and branded design aesthetic. It does not provide hotel rental management, STR rights, or revenue sharing. You rent your unit through a standard residential lease, not a hotel program.
Cipriani is 25-45% more expensive per square foot, delivers 12-18 months later, and is developed by a younger firm. The Cipriani brand may command stronger resale premiums but carries more execution risk. 1428 Brickell offers earlier delivery, lower entry, and Related Group's 40-year track record.
Highest per-sqft price in Brickell creates maximum downside, developer has less local high-rise experience, Cipriani brand untested in Florida residential, yield below risk-free rate, and 50% capital locked for 3+ years without income during construction.
Yes, internationally branded residences in South Florida have achieved 25-45% premiums on resale (Ritz-Carlton, Four Seasons, Faena, St Regis). However, these are established hotel brands with US residential track records. Cipriani's F&B-focused brand is newer to the residential sector and the premium is not yet proven in Florida.
Get Cipriani Miami Investment Analysis
Current availability, deposit schedule, brand premium analysis, and comparison with competing Brickell pre-construction options.