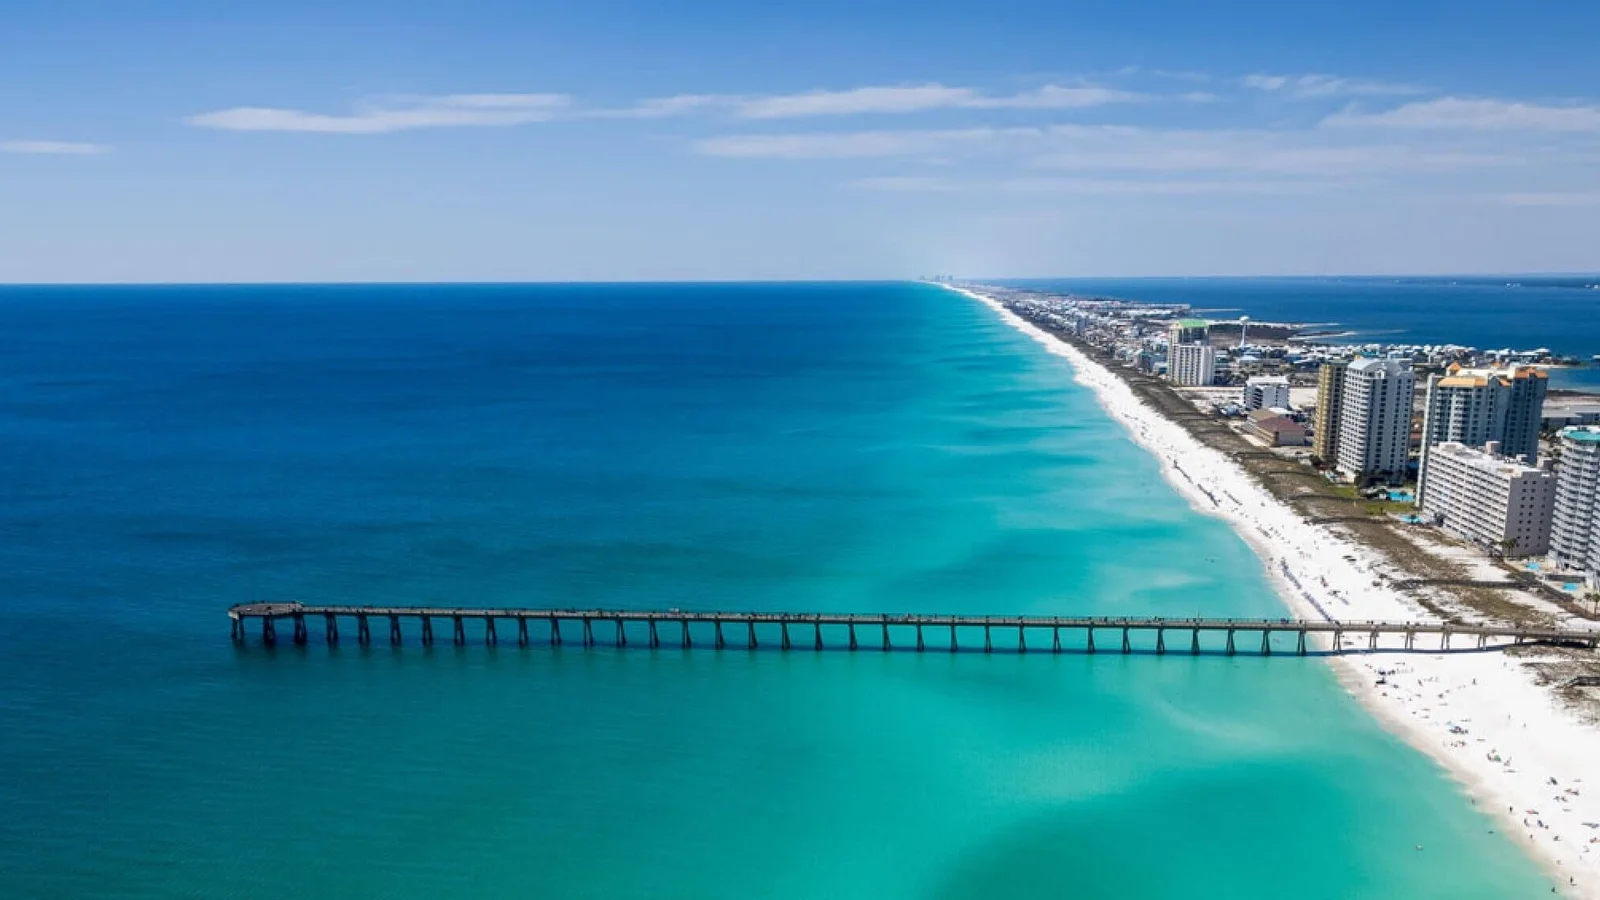
Quick answer: Santa Rosa County levies a 5% tourist development tax, collects it itself, and is not one of the counties Airbnb remits to. The county also owns half of a diligence problem that catches buyers on the coast: Santa Rosa Island crosses a county line, so the beach house you are viewing and the one down the road may answer to different authorities, with different lease administrations and different tax collectors.
One island, two counties
Santa Rosa Island runs east along the Gulf, and the Escambia and Santa Rosa county line crosses it. Pensacola Beach lies on the Escambia side; Navarre Beach lies on the Santa Rosa side.
For a visitor that distinction does not exist. For an owner it decides:
| What it decides | Consequence |
|---|---|
| Which tax collector receives the county tax | separate registration, separate filings |
| Which lease administration applies | different terms and different fee schedules |
| Which county’s building and code enforcement applies | different inspections and processes |
| Which county’s tourist tax rate applies | both are 5%, but they are separate obligations |
An owner with a property on each side of the line runs two registrations and two filing calendars, not one. Confirm the county from the folio and the tax collector’s own record rather than from an address or a marketing description.
The land question again
Navarre Beach shares Pensacola Beach’s history. Barrier island land conveyed by the federal government to county hands in 1947 came with a restriction on conveying it onward to private parties, and the practical answer was long leases rather than sales.
The consequence for a buyer is the same on both sides of the county line. What changes hands in many transactions is a leasehold interest with a finite remaining term, not fee simple title to the ground. Efforts to permit fee simple conversion have run through federal legislation and county resolutions for years and should be treated as live rather than settled.
Three questions answer it for a specific parcel:
- What interest is being conveyed, stated in writing by the title agent?
- How many years remain on the lease?
- Does the lender lend on this island’s leaseholds at all?
The third question is the one that ends purchases late. Ask it before the offer.
The 5% is the owner’s obligation
| Tax | Rate | Who remits it in Santa Rosa County |
|---|---|---|
| Florida state sales tax | state rate, plus any discretionary surtax | commonly handled by the platform |
| Santa Rosa County tourist development tax | 5% | the property owner, directly to the county |
Santa Rosa appears on the Department of Revenue’s schedule as a county-collected jurisdiction, and it is not among the counties for which Airbnb collects the county tax.
That combination produces the most common expensive mistake in this part of Florida. An owner who also operates in a county where the platform handles everything reads a familiar payout summary, sees tax collected, and never opens a county account. Nothing fails. Bookings arrive and guests leave. The only thing that does not happen is the return, and the exposure accumulates from the first night.
Counties reconcile platform booking data against their own registrations. The discovery event is a letter, it covers the whole operating history, and the amount is calculated on gross rent with interest and penalties on top.
Register before the first booking
Open the county account first, then list. At registration establish two things that decide whether the account stays clean:
- The filing frequency the county expects.
- Whether a zero return is required in months with no bookings.
An open account with no filings is what triggers the first enforcement contact, and it does so even when no tax was due. For the state component see Florida sales tax on rentals, and for rates elsewhere see tourist development tax by county.
Licensing
A DBPR vacation rental licence is required where the property meets the transient public lodging test: broadly, rented more than three times in a calendar year for periods under thirty days, or advertised as regularly available for such stays.
On the beach there is a fourth layer beyond state, county and city: the lease itself. Lease terms are enforceable against the leaseholder as a matter of contract, independent of what state preemption says about ordinances. Read the use and assignment provisions before building an income model on the property.
What preemption covers
Florida Statute 509.032(7)(b) bars a local government from prohibiting vacation rentals or regulating the duration or frequency of stays, but the bar does not reach any local law adopted on or before 1 June 2011. Pre-2011 rules survive and may be amended only to become less restrictive.
Three things sit outside that protection entirely:
Generally applicable rules. Noise, parking, waste, occupancy limits and life-safety requirements that apply to all dwellings.
Registration and inspection programmes, which the statute contemplates rather than forbids.
Private restrictions. A lease, a condominium declaration or an association’s rules can restrict letting far more tightly than any government, and no state preemption reaches them. See the HOA and association restrictions checklist.
Gulf Breeze and the mainland
Not every Santa Rosa purchase is on the island. Gulf Breeze, Milton, Pace and the unincorporated mainland are ordinary Florida property with ordinary title, and for those the leasehold section above does not apply.
The tax position is unchanged: 5%, county-collected, owner-remitted, wherever in the county the property sits. What changes is that a mainland purchase is simpler in every other respect, which is worth weighing against the rental premium a beachfront address commands.
The demand is also different in kind. Santa Rosa County contains Naval Air Station Whiting Field at Milton, and military, contractor and training-related demand behaves nothing like beach tourism. Those stays are typically measured in months rather than nights, they are indifferent to season, and they are frequently arranged directly rather than through a booking platform.
That matters for three reasons an owner can act on:
The tax treatment often differs. Stays that cross the six-month line with a written lease leave the transient regime entirely. Stays under it do not, and a direct booking carries no platform to handle even the state component, so both taxes are the owner’s to collect and remit.
Occupancy is steadier. A market driven by postings and training cycles does not empty out in September the way a beach market does, which changes the annual model more than the nightly rate does.
The property specification differs. Long-stay tenants weigh parking, storage, a proper desk and an in-unit washer far more heavily than a Gulf view. Buying beach stock for a mainland demand profile, or the reverse, is the most common mismatch in this county.
The six-month line, and why Navarre sits close to it
Florida’s transient taxes apply to lodging of six months or less. Above that line, with a genuine written lease, the tourist development tax and the transient sales tax both fall away, and so does the vacation rental licensing regime that accompanies them.
Navarre’s market sits unusually close to that line. A large share of Gulf coast winter demand comes from long-stay visitors who would take five months or seven months with equal willingness, and the difference between those two numbers is the difference between a taxed, licensed, monthly-filing operation and an ordinary residential tenancy.
Two points of care:
The term governs, not the intent. A property advertised nightly and let once for eight months was let for eight months. A property advertised as an annual let and broken into two five-month stays was let twice, transiently, and both stays are taxable.
Compare after cost, not on headline rent. A seven-month tenancy at a lower monthly figure frequently beats a nightly season once 5% county tax, transient sales tax, platform commission, cleaning, turnover vacancy, licensing and monthly filings are deducted from the nightly column. Run both models on the same property before choosing one.
Insurance on a barrier island
Wind and flood cover are normally separate from the dwelling policy on the Gulf coast, and a letting operation requires liability cover written for that use rather than owner-occupier cover extended informally.
Do not price this from a percentage. Get real quotes for the specific address and elevation, ask the seller for three years of actual premiums, and establish whether the property is insured privately or through the state-backed insurer of last resort, because that answer moves both the premium and the claims experience. See the Citizens insurance guide and the 1 million dollar liability requirement.
Where the property is a leasehold, add the lease’s own insurance covenants to the list. They are contractual obligations, they can exceed what a lender requires, and they are enforceable against you regardless of what any ordinance says.
Before you buy in Santa Rosa County
- Confirm from the folio which county the parcel is actually in.
- Establish in writing whether the interest is leasehold or fee simple, and the years remaining.
- Get the lease and read its use and assignment provisions.
- Ask the lender, before offering, whether it lends on this island’s leaseholds.
- Register for the county tourist tax before the first booking.
- Confirm the filing frequency and whether zero returns are required.
- Establish whether a DBPR vacation rental licence is required and obtain it.
- Read the association or condominium documents, which can be stricter than any ordinance.
Where this leaves an investor
Santa Rosa is a smaller and quieter market than its neighbours, with a real Gulf season and a tax rate at the middle of the Florida range. The two things that make it different from a generic Florida purchase are both administrative rather than economic: the barrier island’s land tenure, and a county tax that no platform will pay for you.
Both are solved before the offer, with a title agent, a lender and a county registration. For the neighbouring markets see Escambia County, Okaloosa County and Walton County.
Frequently Asked Questions
5% on rentals of six months or less. Santa Rosa is a county-collected jurisdiction on the Department of Revenue's schedule, so the tax is reported and remitted directly to the county, and Santa Rosa is not among the counties where Airbnb collects the county tax for hosts.
Navarre Beach sits on the same barrier island as Pensacola Beach and shares its history: land transferred from the federal government in 1947 on terms that barred private conveyance, occupied under long leases. Fee simple conversion has been pursued for years through federal legislation and county resolutions. Establish the actual interest on the specific parcel with your title agent.
It depends which side of the county line the parcel sits on. Santa Rosa Island runs through both Escambia and Santa Rosa counties, so two houses a short distance apart can answer to different county authorities, file with different tax collectors and sit under different lease administrations.
No. Santa Rosa does not appear among the Florida counties for which Airbnb collects and remits county tourist development tax. Platforms commonly handle the state sales tax component only, leaving the 5% county tax to the owner.
Yes, where the property meets the transient public lodging test, broadly a dwelling rented more than three times a year for periods under thirty days or advertised as regularly available for such stays. County tax registration is separate and additional.
Not by an ordinance adopted after 1 June 2011. Florida Statute 509.032(7)(b) preempts local prohibitions and local regulation of duration or frequency, except where a local law was already in place on that date. Generally applicable rules on noise, parking and occupancy still apply, as do private lease and association restrictions.
Confirm the county, the tenure and the tax position before you offer
Tell us the property you are considering. We will come back with which county the folio sits in, what interest is conveyed and the years remaining, the lease terms, county tourist tax registration steps and filing frequency, and whether a DBPR licence applies.