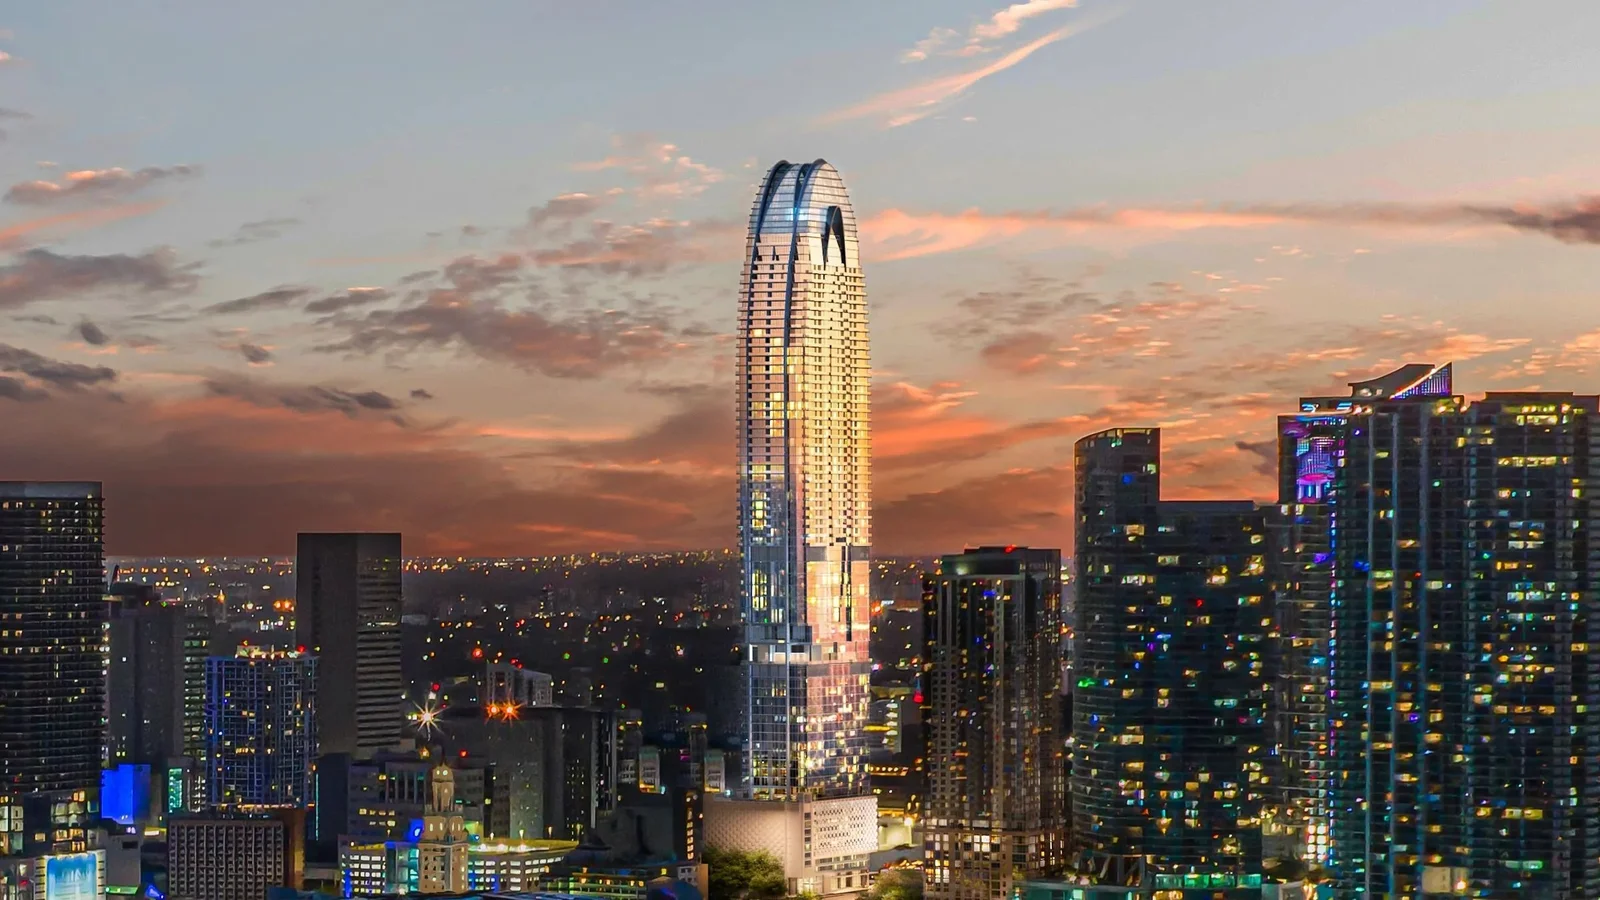
Quick answer: There are two different investments inside this tower and they are separated by floor number. Floors 36 to 50 hold 236 condo-hotel residences under Hilton management that can be let short term. Floors 51 to 70 hold 163 Sky Residences for private living. Same address, same lobby, same renderings, entirely different assets. The first question to ask any agent here is which band the unit sits in, and the second is to see it in writing.
Two products, one address
| Condo-hotel residences | Sky Residences | |
|---|---|---|
| Floors | 36 to 50 | 51 to 70 |
| Number | 236 | 163 |
| Management | Hilton Hotels and Resorts | owner or private manager |
| Short-term letting | contemplated by design | not the intended use |
| Likely buyer | income-seeking investor | resident or second-home owner |
| Resale pool | investors and cash buyers | broader, subject to financing |
This distinction governs everything downstream and it is the most common expensive mistake in condo-hotel towers. A buyer who wanted a residence and bought a hotel-managed unit finds their home enters a rental programme with blackout rules and revenue splits. A buyer who wanted income and bought a Sky Residence finds the short-let model they were shown is not available on their floor.
Ask for the floor number, the unit type as described in the purchase contract, and the declaration section that defines each category. Do not accept a verbal description. In a tower where both products are sold from the same sales gallery with the same renderings, the paperwork is the only thing that distinguishes them.
What the condo-hotel programme actually is
If the unit sits on floors 36 to 50, you are buying into a managed hospitality business rather than a flat you happen to rent out.
The economics of these programmes turn on terms that never appear in a brochure:
- The revenue split. What share of room revenue reaches the owner after the operator’s cut, and is it calculated on gross or on net after operating costs?
- Owner use limits. How many nights per year may you occupy your own residence, and can you choose which nights?
- Blackout periods. Peak season is when the unit earns most and when owners most want to be there. The agreement decides who wins.
- Furniture and refurbishment. Hotel-standard units are refurbished on the operator’s cycle, and owners are usually assessed for it.
- Termination. How long is the management agreement, what happens at expiry, and can an owner exit early?
Ask for the management agreement itself, not a summary. These are the terms that determine whether the published projection is achievable, and they are negotiated between the developer and the operator before any buyer sees them.
The Hilton flag is a genuine asset here: distribution, loyalty programme demand and operating discipline are worth real occupancy. It is also a counterparty with standard terms it is unlikely to vary for an individual purchaser.
The financing answer is probably no, and that matters
Of every building in this series, this one has the clearest agency-eligibility problem, and a buyer should plan around it rather than hope past it.
| Feature | Effect on project eligibility |
|---|---|
| 316-key flagged hotel inside the project | strong indicator of ineligibility |
| 236 residences under hotel management | hotel-type services offered |
| Rental programme participation | rental pooling concerns |
| About 64,000 sq ft of Class A office | counts toward non-residential space limits |
Fannie Mae treats projects operated as a hotel or motel, offering hotel-type services such as daily rentals and central registration, or requiring owners to participate in rental pooling, as ineligible. This tower has all three characteristics in one structure.
The practical consequence is that the conventional thirty-year fixed mortgage should be assumed unavailable across the project until a lender states otherwise in writing. The routes that remain are cash, a portfolio loan held by the originating lender, or a DSCR loan underwritten on the income the unit produces at 25 to 30 per cent down and above conforming pricing. Overseas buyers work through foreign national mortgage programmes.
That is not fatal, and for a condo-hotel unit DSCR is arguably the natural product. It does two things to your position. It raises the deposit and the rate. And it narrows the pool of buyers who can purchase from you later, which is the exit consideration that pre-construction marketing never raises. Ask a DSCR lender specifically whether they will underwrite hotel-programme distributions as income and what documentation they require.
Buying at 75 per cent structure
Construction passed the 50th floor and about 75 per cent structural completion in April 2026, with top-off expected in August 2026 and delivery reported for 2028.
Buying at this stage is different from buying at launch and different again from buying finished:
| Stage | What is settled | What is not |
|---|---|---|
| At launch | price, floor plan | whether it gets built |
| At 75 per cent structure | it will be built | fit-out programme, final budget, turnover date |
| At delivery | everything | nothing left to negotiate |
Structural completion removes the largest pre-construction risk. What remains is the fit-out and commissioning programme, which in a tower containing a full hotel, an office component and two residential products is substantial. A gap between topping out in 2026 and delivery in 2028 is normal for that complexity, and it is also the window in which schedules slip.
Get the deposit schedule from the contract and confirm which instalments are escrowed and which the developer may draw. Get the outside completion date and the buyer’s remedies if it passes. Both matter more at this stage than the renderings do, and both are in the contract rather than the brochure. For how the same questions play out on other Miami projects at this stage, see Aria Reserve and Mercedes-Benz Places.
A 2028 completion puts the SB 4-D milestone trigger near 2053, so structural risk is not part of this decision.
Taxes on a hotel-programme unit
If the unit earns from short stays, the tax stack applies whether the operator or the owner collects it: Florida state sales tax on short-term accommodation plus Miami-Dade tourist development tax, alongside the relevant state licensing.
In a managed programme the operator usually handles collection and remittance, but the obligation and the liability can still reach the owner. Ask explicitly who registers, who remits, who is named on the licence, and what happens if the operator gets it wrong. Ask the same about federal income tax reporting on distributions, which for an overseas owner interacts with withholding rules that a domestic buyer never encounters.
Insurance is the other line. The master policy covers a mixed-use structure containing a hotel, which is a different risk profile from a residential tower, and coastal premiums have repriced every year since 2022. See the Florida property insurance guide, and for the district picture the Miami area page.
Verification checklist before you sign
- Confirm in writing which floor band and which product the unit belongs to, from the contract and the declaration.
- If it is a condo-hotel unit, obtain the full management agreement: revenue split, owner use nights, blackouts, refurbishment assessments, term and termination.
- Get the deposit schedule and confirm which instalments are escrowed.
- Get the outside completion date and the buyer’s remedies if it passes.
- Ask a lender in writing whether the project will be warrantable, and ask a DSCR lender what income evidence they accept from a hotel programme.
- Establish who registers and remits state sales tax and tourist development tax, and who is liable if it is wrong.
- Ask how the residential associations are separated from the hotel and office components, and how shared costs are apportioned.
Which buyer this tower suits
It suits a cash or DSCR investor who specifically wants a Hilton-managed short-let position in Downtown Miami, has read the management agreement, and accepts a narrower resale pool as the price of that income. For that buyer the flag and the location do real work.
It suits a buyer looking for a straightforward Miami residence poorly, and the reason is structural rather than aesthetic. Conventional financing should be assumed unavailable, the building operates as a hotel around you, and the two residential products behave so differently that buying the wrong one is a materially different investment from the one you intended. Establish the floor band first. Everything else follows from it.
Frequently Asked Questions
Floors 36 to 50 hold 236 condo-hotel residences managed by Hilton Hotels and Resorts, which can be offered as short-term rentals. Floors 51 to 70 hold 163 Sky Residences intended for private residential living. They are different products with different economics, different management and different resale markets, and the listing photographs do not distinguish them. Establish which one you are being shown before anything else.
902 feet across 72 storeys at 555 North Miami Avenue, Downtown Miami, containing a 316-key Hilton Miami Bayfront Hotel, 236 Hilton-managed condo-hotel residences, 163 Sky Residences and roughly 64,000 square feet of Class A office space. Architecture is by Behar Font and Partners, and the developer is the Okan Group of Turkey under Bekir Okan.
Construction passed the 50th floor and reached about 75 per cent structural completion in April 2026, with top-off expected in August 2026 and delivery reported for 2028. In a mixed-use tower with a full hotel fit-out, the gap between topping out and occupancy is normal, but confirm the current programme in writing rather than relying on any published date.
The published range runs about $690,000 to $2,800,000 across residences from 447 square foot studios to 2,183 square foot three-bedrooms. Compare prices within the same floor band, because a condo-hotel unit and a Sky Residence are not the same asset even at the same size.
Treat that as unlikely until a lender says otherwise in writing. Fannie Mae treats projects operated as a hotel, offering hotel-type services, or requiring rental pooling as ineligible, and this tower contains a 316-key flagged hotel plus Hilton-managed residences. Where a project is non-warrantable the conventional thirty-year loan is unavailable across the whole project.
A 2028 completion places the 25-year coastal trigger near 2053, which is irrelevant to any realistic hold. The risks here are the deposit committed before closing, the financing route, and choosing the correct product within the building.
Confirm which Okan Tower product you are being offered
Tell us the floor and unit you are considering. We will come back with the product classification from the declaration, the Hilton management agreement terms where it applies, the deposit schedule and escrow treatment, and written lender views on both conventional and DSCR routes.